Navigating Home Improvement Loans in Florida 2026
September 26, 2026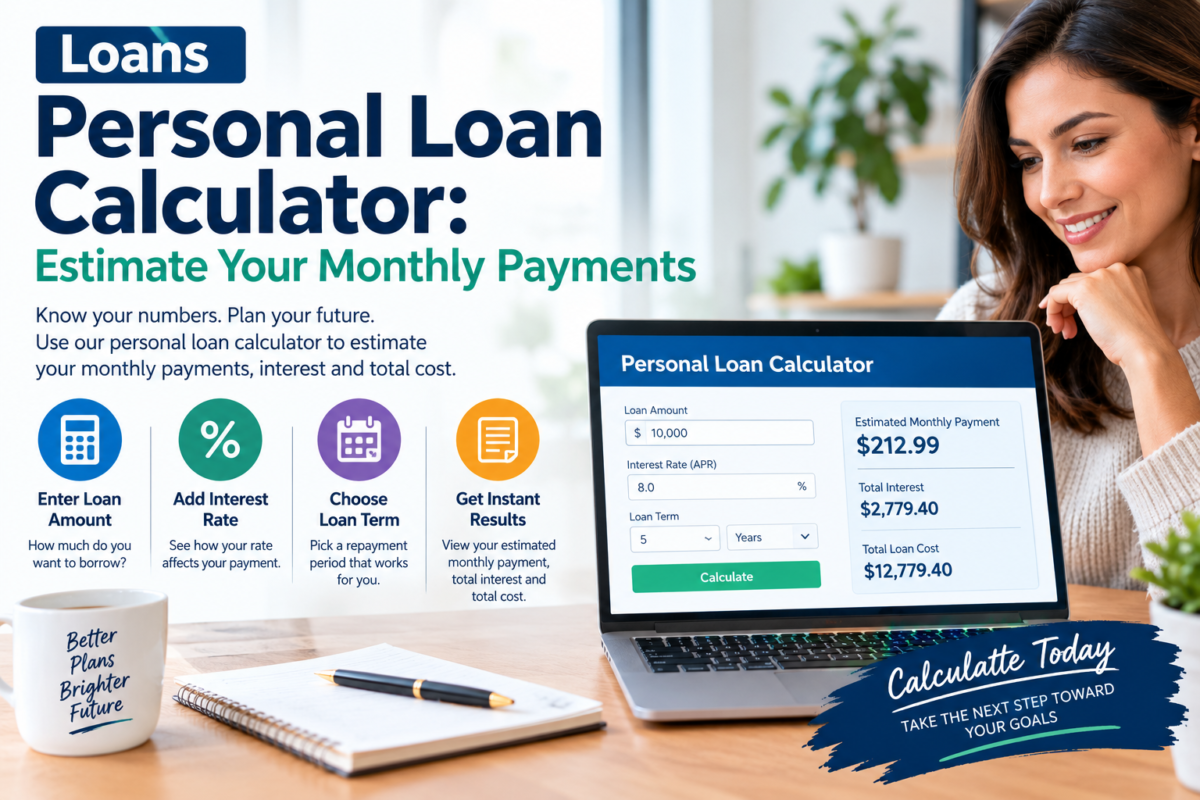
What is a Personal Loan Calculator?
A personal loan calculator is a financial tool designed to assist individuals in estimating their potential loan payments, interest rates, and terms. This user-friendly calculator provides a quick way to evaluate how much one can borrow and the associated costs. By inputting information such as the loan amount, interest rate, and repayment period, users can gain insights into their financial obligations even before applying for a loan.
The primary function of the loans personal loan calculator is to give users a clear view of their expected monthly payments. This enables borrowers to plan their budgets effectively, ensuring they can manage repayments without straining their finances. Additionally, the calculator can illustrate the difference in payments over varying terms and interest rates, helping users make informed decisions. For example, a person may compare the effects of extending a loan term from five to seven years and see how it impacts their monthly installment.
In essence, this tool allows individuals to visualize the potential outcomes of their borrowing decisions. With varying input parameters, users can also adjust the figures to explore possible scenarios, which can be beneficial for those who may be unsure of the amount they wish to borrow. As such, a personal loan calculator acts as a vital resource for consumers navigating the often complex landscape of loans. It empowers borrowers with data-driven insights, thus facilitating a more strategic approach to personal finance management.
Ultimately, understanding how this calculator works is crucial for prospective borrowers. By helping to demystify the loan process, the loans personal loan calculator serves as a supportive stepping stone toward the journey of obtaining personal loans. It is important to utilize this tool to make informed choices about one’s financial future.
How to Use a Personal Loan Calculator
Utilizing a loans personal loan calculator can significantly simplify the process of assessing your loan options. To effectively use such a calculator, you will need to follow a series of straightforward steps. Firstly, enter the amount of money you wish to borrow. This is typically referred to as the loan principal. Make sure to input an amount that accurately reflects your needs, as this will influence the overall calculations.
Next, you should select the interest rate. This rate can often vary based on multiple factors, including your credit score and the lender you choose. It is critical to obtain an estimated interest rate to ensure that the figures generated by the loans personal loan calculator are as accurate as possible. Many calculators provide an option to browse typical rates, allowing you to begin with an informed estimate.
Once you have entered the desired loan amount and interest rate, the next step is to select the loan term. This refers to the duration over which you will be repaying the loan, commonly ranging from three to five years, or longer. The term you choose will impact your monthly payments and the total interest paid over the life of the loan, so consider your financial situation carefully.
After entering all relevant information, the loans personal loan calculator will generate a detailed breakdown of your estimated monthly payment, total payment over the life of the loan, and the total interest paid. It may also present an amortization schedule, which outlines how each payment reduces your loan balance over time. Understanding this information is essential, as it allows you to evaluate whether the loan aligns with your financial goals.
Utilizing a personal loan calculator effectively can provide clarity and confidence in your borrowing decisions, making it an indispensable tool when considering a loan.
Benefits of Using a Personal Loan Calculator
Utilizing a loans personal loan calculator is an effective way to streamline the process of obtaining a personal loan. One of the primary advantages of employing such a tool is that it greatly aids in budgeting. By inputting specific loan amounts and interest rates, borrowers can easily determine monthly payment estimates, helping individuals to integrate these figures into their financial planning. This proactive approach ensures that individuals only consider loans that align with their budgetary constraints.
Moreover, a personal loan calculator allows users to compare different loan offers efficiently. As various lenders may provide different interest rates and repayment terms, having a calculator on hand enables potential borrowers to evaluate these differences thoroughly. This side-by-side comparison feature empowers individuals to make informed decisions, ensuring that they secure the most favorable terms for their financial situation.
Informed financial decisions are crucial when it comes to borrowing money. A personal loan calculator not only simplifies the numerical aspects of loan management but also enhances clarity regarding overall costs associated with loans. Understanding total repayment amounts, interest accrued, and the implications of varying loan terms can significantly influence a borrower’s choices. Thus, by leveraging a loans personal loan calculator, users can pivot away from impulsive decisions, ensuring that they remain committed to responsible borrowing practices.
In summary, the availability of a personal loan calculator empowers individuals to budget effectively, compare terms, and make sound financial decisions regarding personal loans. This tool serves as a valuable resource, making the borrowing process more transparent and manageable for all borrowers.
Factors to Consider When Calculating Personal Loans
When using a loans personal loan calculator, it is essential to understand the various factors that can significantly impact the calculations and subsequent loan decisions. One of the primary elements is the credit score of the borrower. A higher credit score typically results in more favorable interest rates, while a lower score may necessitate higher rates or, in some cases, disqualification from certain loan products. This highlights the importance of maintaining a healthy credit score to ensure the best loan terms possible.
Another critical factor is the amount of loan desired. Personal loans can vary widely, and the amount borrowed directly influences repayment terms and interest calculations. With most personal loans, larger sums can lead to greater total interest paid over time, especially if the repayment period is extended. Therefore, borrowers should carefully assess how much they need and explore borrowing only what is necessary to minimize costs.
Interest rates also play a vital role in the calculation of personal loans. These rates can fluctuate based on various market conditions and borrower qualifications. Fixed rates offer stability in monthly payments, while variable rates may start lower but can increase over time. Prospective borrowers should evaluate both types of interest rates to determine which option aligns better with their financial situation.
Lastly, the repayment period is another significant aspect to consider when utilizing a loans personal loan calculator. Longer repayment terms may lead to lower monthly payments, but they often result in a larger total interest cost over time. Conversely, shorter terms can mean higher monthly payments but less interest accumulation overall. Borrowers must weigh these options carefully to select a repayment period that fits their budget without compromising their financial health.
Understanding Interest Rates
When considering the loans personal loan calculator, one crucial aspect to understand is the type of interest rate associated with a personal loan. Interest rates can be broadly categorized into two types: fixed rates and variable rates. Each type offers distinct advantages and disadvantages that can significantly affect the total cost of borrowing.
Fixed interest rates remain constant throughout the term of the loan. This means that the borrower’s monthly payments will not change, providing a sense of stability and predictability in financial planning. For many individuals using a loans personal loan calculator, the fixed-rate option is appealing because it simplifies budgeting. Knowing that the payment will remain unchanged allows borrowers to forecast their expenses with greater accuracy, which is especially essential for long-term financial commitments.
On the other hand, variable interest rates can fluctuate over time, often tied to a benchmark interest rate or index. While initial rates may be lower than those of fixed-rate loans, they come with an inherent risk; as the benchmark rate rises, so too will the borrower’s interest payments. This variability can result in lower initial costs, but unpredictability can lead to larger payments down the line. Borrowers who consider using a loans personal loan calculator should carefully weigh the potential benefits and risks associated with variable rates.
Ultimately, the choice between fixed and variable rates should align with the borrower’s financial situation and risk tolerance. Understanding these two types of interest rates is vital for making informed decisions regarding personal loans. Being aware of how each rate impacts overall loan costs enables borrowers to utilize the loans personal loan calculator more effectively, ensuring they select the right option for their needs.
Repayment Plans and Their Implications
When considering a personal loan, it’s essential to understand the various repayment plans available, as these options can significantly affect both the monthly payments and the total amount paid over the loan’s duration. Personal loans typically offer a range of repayment terms, generally spanning from one to seven years. The choice of a repayment plan can be as critical as the initial loan amount itself, directly influencing your financial obligations and budgeting strategies.
One common repayment method is the fixed-rate plan, where the interest rate remains constant throughout the loan term. This approach allows borrowers to predict their monthly payments accurately and facilitates better financial planning. Conversely, there are variable-rate options, where interest rates fluctuate based on market conditions. While these may start lower than fixed rates, they also entail the risk of increasing payments over time, making budgeting more challenging.
Another important aspect of repayment plans is the potential for different payment schedules. Some lenders allow for weekly or bi-weekly repayment options, which can help borrowers reduce interest costs due to the more frequent reduction of principal. Understanding the intricacies of these options can empower individuals to select a plan that best aligns with their financial situation.
Additional factors, such as prepayment penalties, should also be considered. Certain lenders impose fees if borrowers choose to pay off their loans early, which can negate the benefits of savings accrued through reduced interest payments. Hence, it is crucial to read the terms carefully and evaluate how each repayment plan impacts the total cost of the loan.
In conclusion, selecting the right repayment plan for a personal loan is a decision that can significantly impact an individual’s financial landscape. By understanding the implications of various repayment options, borrowers can make better-informed choices and potentially save money over the life of their loans.
Common Mistakes to Avoid with Personal Loan Calculators
Using a loans personal loan calculator can be an effective method for borrowers to estimate their potential loan amounts, interest rates, and repayment terms. However, several common mistakes can lead to misguided expectations and poor financial decisions. Recognizing these pitfalls is crucial for ensuring accurate calculations.
One common error is entering incorrect data into the calculator. Borrowers often overlook the importance of providing precise figures for their income, existing debts, and credit scores. Any inaccuracies in these inputs can skew the results, leading to an unrealistic view of what one can afford. Thus, verifying all entered information before performing calculations is essential to obtaining reliable estimates.
Another frequent mistake arises when borrowers do not understand the terms of the loan for which they are calculating. It is vital to comprehend loan features, such as the difference between fixed and variable interest rates. For instance, a fixed interest rate will provide consistent repayment amounts, while a variable rate may fluctuate over time. This understanding helps individuals make well-informed decisions regarding their financing options.
Borrowers sometimes rely too heavily on the calculator’s output without considering additional costs associated with loans, such as origination fees, closing costs, and insurance. These factors can significantly impact the total loan expense, so it is advisable to integrate these into the overall budgeting which the loans personal loan calculator may not fully encompass.
To avoid misunderstandings, it is recommended that users familiarize themselves with the calculator’s parameters and ensure that they are aware of any assumptions made by the tool. By being cautious and double-checking both inputs and outputs of the loans personal loan calculator, individuals can enhance their decision-making process significantly. Ultimately, a sound understanding of these potential mistakes can empower borrowers to utilize personal loan calculators effectively and more accurately inform their financial choices.
Real-World Scenarios Using a Personal Loan Calculator
In today’s financial landscape, utilizing a loans personal loan calculator can bring clarity and aid in making informed decisions. This tool provides valuable insights tailored to various scenarios that individuals frequently encounter.
One common situation is when an individual is looking to consolidate debt. For instance, Jane, a working professional, has accumulated several high-interest credit card debts. By employing a personal loan calculator, she can estimate how much she needs to borrow to pay off these debts and what her monthly payments will look like at different interest rates. This enables her to compare her current payments with the potential new loan, helping her understand the potential savings and whether this move is financially sound.
Another example involves funding a major purchase, such as a home renovation. John and his spouse want to renovate their kitchen, with costs expected to reach $15,000. By inputting the desired amount into the loans personal loan calculator, they can evaluate various loan terms and interest rates. This will give them a clear picture of their monthly payment responsibilities and the overall cost of the loan, allowing them to align the expense with their budget.
Furthermore, consider Sarah, a recent college graduate. She is considering taking out a personal loan to cover unexpected medical expenses. By utilizing the calculator, Sarah can determine different borrowing options and the financial implications of each. This strategic approach helps her avoid overextending her finances while addressing her pressing needs.
In summary, these real-world examples illustrate the diverse applications of a personal loan calculator, demonstrating its critical role in making sound financial decisions. Whether managing debt, funding significant expenses, or navigating emergencies, this tool facilitates personalized financial planning.
Conclusion: Making Informed Decisions with Personal Loan Calculators
In the complex world of borrowing, personal loan calculators emerge as essential tools that assist potential borrowers in making informed financial decisions. By leveraging a loans personal loan calculator, individuals can gain insights into various aspects of their borrowing, including monthly payments, total interest, and loan terms. This understanding is crucial in navigating the often overwhelming landscape of loan options.
One of the primary benefits of using a personal loan calculator is the ability to simulate different borrowing scenarios. Borrowers can input varying amounts, interest rates, and loan periods to see how these factors influence their repayment obligations. This feature empowers users by allowing them to compare multiple lenders and loan offerings, ensuring that they choose terms that align with their financial goals.
Moreover, personal loan calculators contribute to financial literacy. They demystify the borrowing process by providing clarity on how loans function and the implications of interest rates and repayment timelines. As borrowers become more informed, they can approach lending decisions with confidence, reducing the risk of falling into unfavorable agreements. This knowledge is particularly beneficial for first-time borrowers who may not fully understand the nuances of loans.
In summary, utilizing a loans personal loan calculator is a pivotal step for anyone considering a personal loan. By taking the time to assess their financial situation and using the analytical capabilities of these calculators, borrowers can secure better terms and ensure their financial wellbeing. In an era where personal finance tools are increasingly accessible, empowering oneself with the right information becomes a vital component of successful borrowing.
FAQ: Personal Loan Calculator — Estimate Your Monthly Payments
1. What is a personal loan calculator?
A personal loan calculator is a tool that estimates your monthly loan payment based on the loan amount, interest rate, and repayment term. It can help you understand potential borrowing costs before applying for a loan.
2. How does a personal loan calculator work?
You typically enter:
- Loan amount
- Annual interest rate
- Loan term
The calculator uses these details to estimate your monthly payment and, depending on the calculator, the total interest and total amount you may repay.
3. What information do I need to use a personal loan calculator?
You generally need the amount you want to borrow, the estimated annual percentage rate (APR) or interest rate, and the desired repayment period.
4. How is a personal loan monthly payment calculated?
For a typical fixed-rate installment loan, the payment is calculated using the loan principal, periodic interest rate, and number of payments. A common formula is:
M = P × [r(1+r)ⁿ] / [(1+r)ⁿ − 1]
Where M is the monthly payment, P is the loan principal, r is the monthly interest rate, and n is the total number of monthly payments.
5. Does a personal loan calculator include interest?
Most calculators can estimate the interest you will pay over the life of the loan. However, the result depends on the information entered and whether the calculator accounts for applicable fees.
6. Does the calculator show the total cost of a personal loan?
Many calculators show both estimated total payments and total interest. Check whether the calculator includes origination fees or other charges because these can affect the actual cost of borrowing.
7. How does the loan term affect my monthly payment?
A longer repayment term generally results in lower monthly payments but can result in more interest paid over the life of the loan. A shorter term may increase monthly payments while reducing the total interest paid.
8. How does the interest rate affect my payment?
Generally, a higher interest rate increases both the monthly payment and the total interest cost, assuming the loan amount and term remain the same.
9. Is a personal loan calculator accurate?
It can provide a useful estimate, but it does not guarantee the rate or terms a lender will offer. Your actual rate and payment may depend on factors such as credit history, income, loan amount, lender requirements, and fees.
10. Does using a personal loan calculator affect my credit score?
Simply using a calculator does not normally involve a credit application or credit inquiry, so it generally does not affect your credit score. A lender’s subsequent application or credit check may have different implications.
11. Can I use the calculator to compare different loan offers?
Yes. Enter the loan amount, APR, and term for each offer and compare the estimated monthly payment, total interest, and total repayment amount. Also review fees and other terms that may not be reflected in the basic calculation.
12. Can I calculate a personal loan payment before applying?
Yes. Using a calculator before applying can help you estimate affordability and determine which loan amount and repayment term fit your budget.
13. What is APR, and why is it important?
APR, or annual percentage rate, is a measure used to express the cost of borrowing on an annualized basis. Depending on the lender and applicable rules, APR can incorporate certain fees as well as interest, making it useful when comparing loan offers.
14. Can I use a personal loan calculator for debt consolidation?
Yes. You can enter the amount you plan to consolidate and compare the estimated payment and total cost with your existing debts. Consider fees, repayment terms, and whether the new loan actually reduces your overall borrowing costs.
15. Does a personal loan calculator tell me whether I will qualify?
No. A calculator estimates payments; it does not determine loan approval. Lenders may consider credit history, income, employment, debt obligations, and other eligibility criteria.
16. What should I consider besides the monthly payment?
Look at the APR, total interest, fees, repayment term, prepayment conditions, and total amount repaid. A loan with a lower monthly payment can still cost more overall if it has a longer term or higher borrowing costs.
Read More: