How does minority startup business loans work for small businesses
September 24, 2026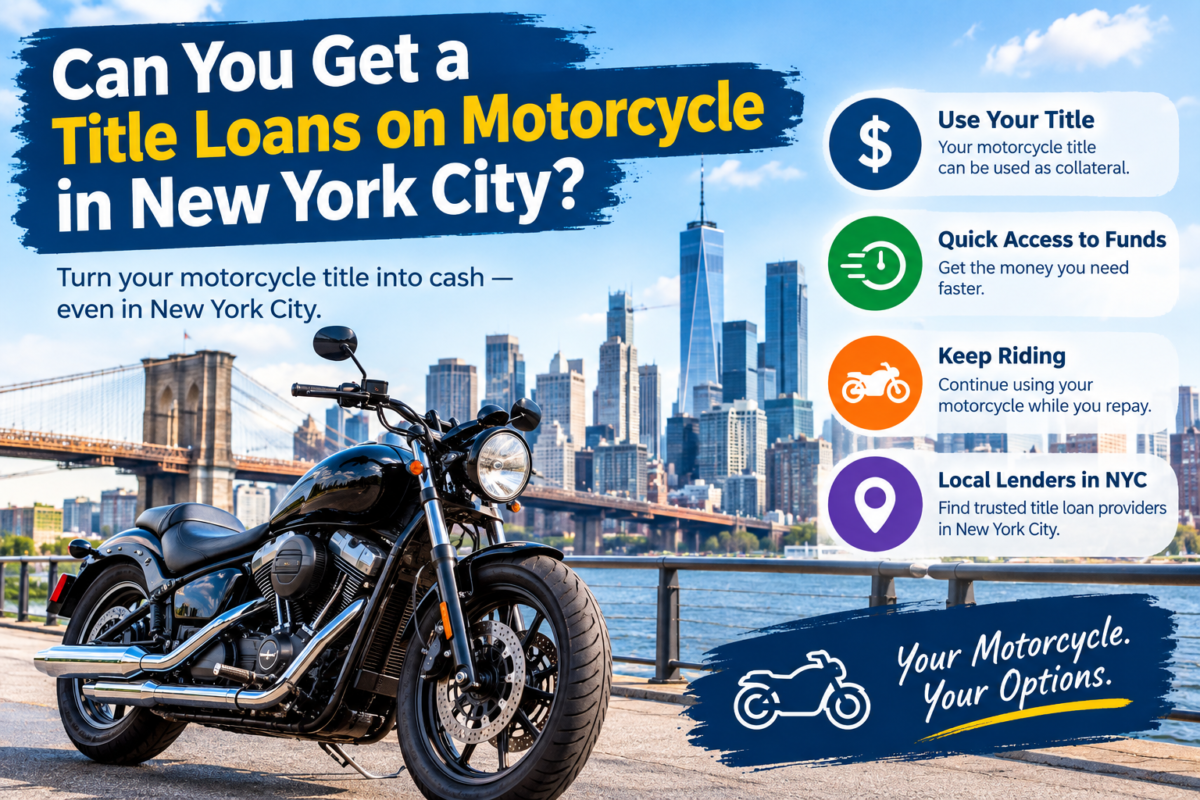
Understanding Title Loans
Title loans, a form of secured lending, allow borrowers to use their vehicles as collateral, providing a potential source of quick cash. The basic principle hinges on the lender using the title of the vehicle to secure the loan. In New York City, motorcycle owners may find themselves asking, can you get a title loan on a motorcycle in New York City? The answer is yes, provided the motorcycle is fully owned and has a clear title.
To obtain a title loan, several pieces of documentation are typically required. The borrower must present the motorcycle title, valid identification, and proof of income. Depending on the lender, additional documentation such as proof of residence or vehicle registration may also be necessary. This information allows the lender to assess both the collateral’s value and the borrower’s ability to repay the loan.
One primary advantage of title loans is their swift approval process. Many lenders can approve loans within hours, providing immediate access to funds, which can be particularly beneficial during emergencies. However, title loans come with notable disadvantages, including high-interest rates that can ranging from 25% to 300% annually, depending on the lender’s terms. Moreover, the risk of losing the motorcycle if the loan defaults poses a significant concern for borrowers.
Repayment terms for title loans vary but typically span from 30 days to a few months. Borrowers should be aware that failure to repay the loan on time can lead to the lender repossessing the motorcycle to recover their losses. Hence, while title loans can offer a swift solution to financial troubles for motorcycle owners, it is crucial to thoroughly assess the cost and implications associated with them. This understanding is essential for making an informed decision about securing funds through this means.
Motorcycles in the Financial Landscape
Motorcycles hold significant appeal in New York City due to their unique advantages in an urban setting. They offer a practical solution for navigating congested streets and often provide a more economical option compared to cars. As a result, the popularity of motorcycles as a mode of transportation has seen a marked increase in recent years. Various types of motorcycles are frequently financed, ranging from cruisers and sport bikes to touring motorcycles, each serving different purposes and catering to distinct consumer preferences.
The appreciation or depreciation in value of motorcycles is an important factor for potential borrowers to consider when exploring options like title loans. Unlike cars, which can depreciate significantly as soon as they are driven off the lot, certain motorcycles may hold their value better over time, particularly classic models or motorcycles from reputable brands. This fluctuating value can influence the terms of a title loan, as lenders typically evaluate the market value of the collateral to determine the loan amount.
In the context of title loans, the question arises: can you get a title loan on a motorcycle in New York City? The answer is generally affirmative, provided that the motorcycle meets specific criteria set forth by lenders. It is essential for borrowers to present valid documentation proving ownership and to ensure that the motorcycle is free from liens. Lenders assess the motorcycle’s current market value during the approval process, which can directly impact the borrowing amount. Thus, understanding the motorcycle’s value and the factors that contribute to its depreciation or appreciation is vital for individuals seeking title loans.
Overall, the financial landscape for motorcycles in New York City illustrates both the opportunities and challenges associated with financing these vehicles. As borrowers navigate the intricacies of obtaining a title loan, awareness of the motorcycle market can play a crucial role in securing favorable financing options.
Eligibility Requirements for Title Loans on Motorcycles
To determine can you get a title loan on a motorcycle in New York City, it is essential to understand the specific eligibility requirements involved. The first critical factor is ownership; the motorcycle must be completely paid off and legally owned by the individual seeking the loan. This means that there should be no outstanding liens on the title, and the individual must provide documentation proving their ownership. Without clear title, obtaining a loan would not be possible.
Additionally, borrowers must demonstrate adequate insurance coverage on the motorcycle. Lenders typically require full coverage insurance, which includes both collision and comprehensive policies. This requirement is crucial as it protects the lender’s investment should an accident or theft occur. Applicants need to present proof of insurance as part of the loan application process.
The condition of the motorcycle plays an important role as well. Lenders often assess the motorcycle’s make, model, year, and overall condition to determine its market value. A motorcycle in poor condition may not qualify for a loan or may result in lower lending amounts. Therefore, potential borrowers should ensure their motorcycle is well-maintained and functioning optimally to enhance the chances of approval.
In addition to the above factors, lenders may consider the applicant’s credit history, although title loans are often less stringent than traditional loans regarding credit scores. Nevertheless, the borrower’s financial history can influence the terms and interest rates offered. Understanding these eligibility criteria is vital for anyone considering a title loan on their motorcycle in New York City, as meeting these requirements will provide a smoother borrowing experience.
The Process of Applying for a Title Loan on a Motorcycle
Applying for a title loan on a motorcycle can be a straightforward process if you are prepared and understand the steps involved. First, it is crucial to assess whether you are eligible for a loan by ensuring that you have a clear motorcycle title in your name. A clean title indicates that there are no liens against the motorcycle, which is essential since lenders require full ownership to provide financing.
Once you have confirmed that your title is clear, you should gather all necessary documentation. This typically includes a government-issued ID, proof of income, and proof of residency. Some lenders might also request additional documentation, such as photographs of the motorcycle or a description of its condition. Being organized and having these documents ready can expedite the application process.
The next step involves choosing a lender. In New York City, there are various financial institutions and specialized lenders that offer title loans on motorcycles. It is advisable to compare interest rates, repayment terms, and customer reviews to find the most suitable option. Ensure that you understand the terms and conditions of the loan before proceeding.
When you select a lender, you can begin the application process. This can often be done online, over the phone, or in person. During the application, the lender will typically ask for details about your motorcycle, including make, model, year, and current mileage. They will also evaluate your creditworthiness based on your financial history.
After your application is submitted, the lender will review your information and make a decision. If approved, you will receive a loan offer, including the amount, interest rate, and repayment terms. It is important to read through this offer carefully. If you agree to the terms, you will sign the loan documents, and the funds can be disbursed, often on the same day. Throughout this process, you might find yourself asking, “can you get a title loan on a motorcycle in New York City,” and understanding these steps can help clarify that possibility.
Overall, being informed about the process of applying for a title loan on a motorcycle can help you navigate the situation efficiently, making informed decisions along the way.
Interest Rates and Fees Associated with Motorcycle Title Loans
When considering can you get a title loan on a motorcycle in New York City, it is crucial to understand the financial aspects involved, particularly interest rates and associated fees. Title loans can be an appealing option for those in need of immediate funds, as they typically use the borrower’s motorcycle as collateral, allowing for a potentially faster approval process.
Interest rates on title loans can vary widely based on the lender, the borrower’s creditworthiness, and the market conditions. In New York City, individuals may encounter annual percentage rates (APRs) averaging from 20% up to 36%. While this may seem competitive compared to some forms of unsecured loans or credit cards, it is essential to evaluate the total cost over the loan period. Because title loans are often short-term, the effective interest rate can be quite high if the loan is not repaid quickly.
Moreover, borrowers should also be aware of potential hidden fees associated with title loans on motorcycles. Some lenders may impose origination fees, document fees, or even late payment penalties that can inflate the total amount owed significantly. It is advisable to read all loan documents thoroughly and ask lenders about any possible charges to avoid unexpected costs.
When contrasting title loans with other borrowing options in New York City, such as personal loans or payday loans, it is important to take into account not only the interest rates but also the risks involved. Personal loans typically offer lower interest rates for applicants with good credit histories, while payday loans can have even higher costs than title loans. Ultimately, potential borrowers should carefully consider how motorcycle title loans fit into their financial strategies, ensuring that they fully grasp the conditions and fees that will accompany this type of loan.
Common Misconceptions About Title Loans
Title loans on motorcycles have become increasingly popular; however, they are often surrounded by numerous myths and misconceptions. A common query people have is, can you get a title loan on a motorcycle in New York City? Some believe that such loans are only for vehicles like cars, overlooking their availability for motorcycles as well. This misunderstanding can prevent individuals from accessing financial resources that they might need in times of distress.
One prevalent myth is that title loans are synonymous with predatory lending. While it is true that some lenders may exploit borrowers, especially in desperate situations, not all title loan companies operate unethically. Many reputable lenders provide fair terms and transparent practices. It is crucial for borrowers to conduct thorough research and read reviews to identify trustworthy lenders, thus dispelling this concern about predatory lending.
Furthermore, there exists a fear regarding ownership risks when securing a title loan on a motorcycle. Some prospective borrowers worry that they will lose their motorcycle during the repayment period. However, under normal circumstances, borrowers retain possession of their vehicle, allowing them to continue using it while making loan payments. The lender holds the title as collateral until the loan is paid off, which means ownership remains with the borrower as long as the terms of the loan are upheld.
Moreover, many people think that obtaining a title loan is too complicated or time-consuming. In actuality, the process of securing a title loan is relatively straightforward. Borrowers are usually required to present proof of ownership, along with essential documentation, including identification and income verification. Provided everything is in order, many lenders can process the loan quickly, providing timely access to funds.
Dispelling these misconceptions about title loans on motorcycles aids potential borrowers in making informed decisions. Understanding that title loans can be a viable option for motorcycle owners in New York City is essential to realizing their financial potential.
Repayment Options and Strategies
When considering the question, can you get a title loan on a motorcycle in New York City, it is important to understand the various repayment options available. Title loans are designed to provide quick access to funds, but managing repayments is crucial to maintaining ownership of the motorcycle used as collateral. Borrowers typically have multiple options for repaying these loans.
One common repayment method is to make monthly installments, which allows the borrower to spread the repayment over a set period. This approach is beneficial as it can help borrowers create a manageable budget while ensuring that payments are made promptly. Setting auto-pay options may also be useful in ensuring that repayments are consistently made on time.
Another viable strategy involves lump-sum payments. Some lenders offer flexibility whereby a borrower can pay more than the minimum due amount or repay the full loan early. This option can reduce overall interest costs and hasten the liberation from the debt. However, it is wise to check if early repayment incurs penalties.
Additionally, borrowers could consider negotiating the terms of their loan with the lender. This can include requesting an extension on the repayment period, which could alleviate some immediate financial pressure. Nevertheless, it is crucial for borrowers to fully understand the implications of altering payment terms, as this may result in accruing more interest over time.
To manage repayments effectively and avoid risking ownership of the motorcycle, maintaining open communication with lenders is vital. Furthermore, allocating a portion of monthly income specifically for loan repayments can help in achieving financial stability and facilitating timely payment. Utilizing budgeting tools or apps may also assist borrowers in tracking their expenses and managing their finances.
In conclusion, exploring the repayment options and strategies for title loans on motorcycles in New York City is essential for ensuring that borrowers can meet their financial obligations while preserving ownership of their vehicles. By understanding the available alternatives and employing sound financial practices, individuals can navigate their title loan commitments effectively.
Alternatives to Title Loans for Motorcycle Financing
While title loans on motorcycles can provide immediate cash relief, they are not the only financing options available to motorcycle owners in New York City. For individuals seeking alternative forms of funding, there are several viable methods that can alleviate financial concerns without resorting to the risks often associated with title loans.
One of the most accessible alternatives is a personal loan. Personal loans typically offer flexible terms and competitive interest rates, making them a suitable choice for those looking to finance their motorcycle purchase or cover unexpected expenses. Unlike title loans, personal loans do not require the borrower to put their motorcycle at risk, thus providing peace of mind during the repayment period. Many lenders, including banks and online financial institutions, offer personal loans tailored to the borrowing needs of individuals.
Credit unions are another excellent option for motorcycle owners seeking financing. These member-owned financial cooperatives often provide lower interest rates and more favorable terms compared to traditional banks. By becoming a member of a credit union, borrowers can access loans specifically designed for vehicle purchases, which may include motorcycles. Credit unions typically emphasize personalized customer service, ensuring that members receive the guidance they need to make informed financial decisions.
Traditional bank loans remain a reliable method for financing motorcycles as well. Many banks offer motorcycle loans with fixed terms and transparent fee structures. Borrowers can often take advantage of specialized loan products tailored to motorcycle purchases, giving them a sense of security compared to alternative lending options like title loans. Additionally, by maintaining a good credit score, borrowers can secure favorable terms, which can lead to substantial savings over the loan’s duration.
Ultimately, while the question of “can you get a title loan on a motorcycle in New York City” may arise, exploring alternatives such as personal loans, credit union financing, and traditional bank loans can provide motorcycle owners with more desirable options for their financial needs.
Conclusion: Making an Informed Decision
In the landscape of financial options available to motorcycle owners, understanding the nuance of title loans is paramount. When considering if can you get a title loan on a motorcycle in New York City, it is crucial to approach this inquiry with a comprehensive perspective. Title loans can provide immediate financial relief but may come with significant risks that can affect your broader financial health.
Motorcycle owners should conduct thorough research before proceeding with a title loan. This includes understanding the terms of the loan, the interest rates, and the potential penalties for non-repayment. Many lenders offer varying terms based on the condition and value of the motorcycle, and therefore, obtaining multiple quotes is advisable. Such an approach can help individuals find the most favorable terms tailored to their specific circumstances.
Additionally, assessing personal financial situations is essential before committing to a title loan. Owners must evaluate their ability to repay the loan amount within the stipulated time frame to avoid the risks of losing their asset. A well-structured repayment plan can mitigate these risks substantially. Engaging a financial advisor or utilizing financial planning tools can also be beneficial in making a well-informed decision.
In conclusion, the decision of securing a title loan on a motorcycle in New York City should be taken after careful consideration and planning. By understanding the loan conditions, exploring alternative options, and assessing personal finances, motorcycle owners can navigate the process more effectively and make informed choices that align with their financial goals. This thorough approach not only safeguards the motorcycle but also contributes to overall financial stability.
FAQs: Can You Get a Title Loan on a Motorcycle in New York City?
1. Can you get a title loan on a motorcycle in New York City?
Yes, motorcycle title loans may be available in some locations, but New York City and New York State have specific lending regulations that affect how vehicle title loans can be offered. Borrowers should check whether a lender is licensed and follows state requirements.
2. What is a motorcycle title loan?
A motorcycle title loan is a secured loan where you use your motorcycle’s title as collateral. The lender may approve the loan based on the motorcycle’s value, condition, and your ability to repay, while you typically continue using the motorcycle during the loan term.
3. Do I need a clear motorcycle title to get a title loan in NYC?
Most lenders require a clear title, meaning there are no existing liens or unpaid loans attached to the motorcycle. Requirements can vary by lender, so it is important to confirm eligibility before applying.
4. How much can I borrow with a motorcycle title loan?
The loan amount depends on factors such as your motorcycle’s make, model, age, condition, market value, and the lender’s policies. Some lenders offer a percentage of the motorcycle’s estimated value.
5. Can I keep riding my motorcycle after getting a title loan?
In many title loan arrangements, borrowers can continue using their motorcycle while the lender holds the title as security. However, the exact terms depend on the loan agreement.
6. What documents are needed for a motorcycle title loan in New York City?
Common requirements may include a government-issued ID, motorcycle title, proof of income, proof of residence, registration, and motorcycle information. Individual lenders may request additional documents.
7. Are motorcycle title loans expensive?
Costs vary depending on the lender, loan amount, repayment period, and applicable fees. Before accepting a loan, review the interest rate, fees, repayment terms, and potential consequences of missed payments.
8. Can I get a motorcycle title loan with bad credit in NYC?
Some lenders focus more on the value of the motorcycle and ownership documents rather than credit history. However, approval requirements vary, and borrowers should compare options carefully.
9. What happens if I cannot repay a motorcycle title loan?
If you fail to meet the repayment terms, the lender may have rights to take action against the motorcycle according to the loan agreement and applicable laws. Always review the contract before signing.