Low-Interest Home Loans in the United States
November 2, 2026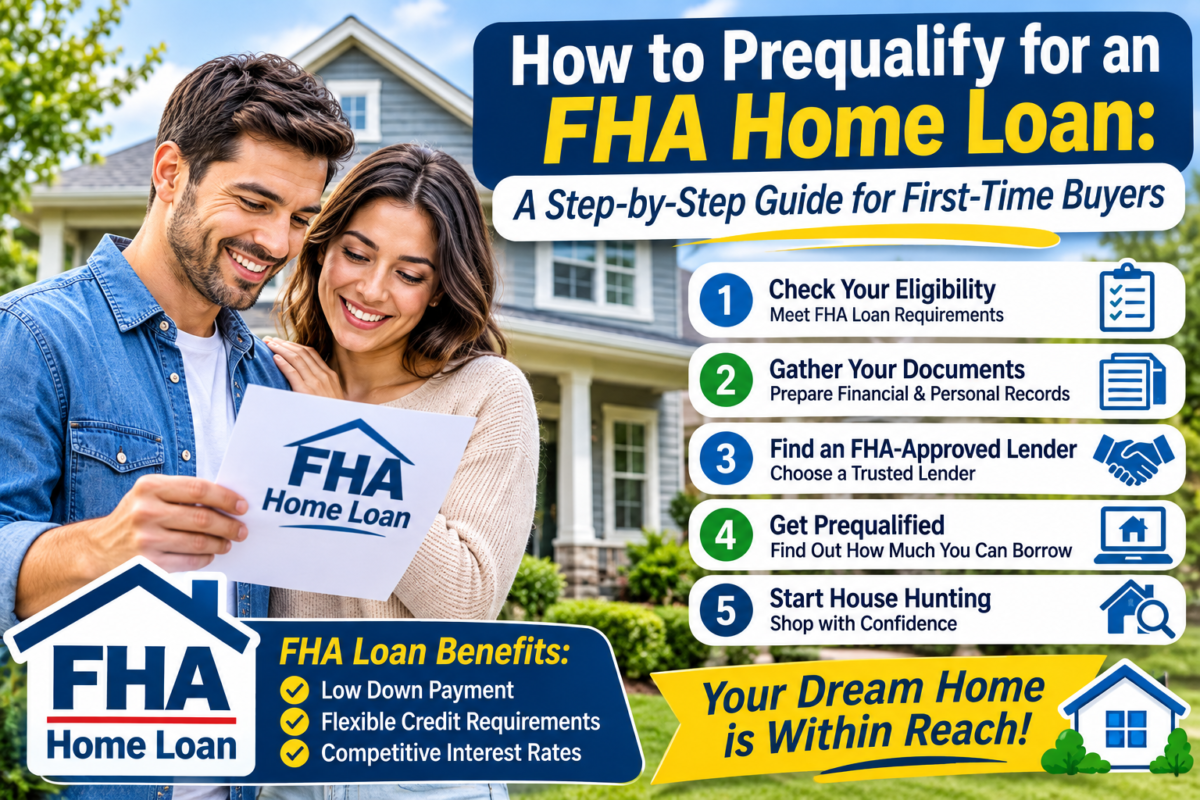
Buying a home is an important financial decision, especially if you are purchasing your first property. However, saving for a down payment, meeting credit requirements, and understanding mortgage options can make the process feel overwhelming. If you are looking for an affordable way to become a homeowner, an FHA loan may be worth considering.
FHA loans are mortgages insured by the Federal Housing Administration (FHA), which is part of the U.S. Department of Housing and Urban Development (HUD). These loans are designed to make homeownership more accessible by offering flexible qualification guidelines and relatively low down payment requirements.
Before starting your home search, understanding how to prequalify for an FHA home loan can help you determine whether you may meet the basic lending requirements and how much you might be able to borrow.
The prequalification process gives you an early idea of your borrowing capacity, monthly mortgage payments, and potential down payment. It can also help you identify financial issues that need attention before submitting a formal mortgage application.
In this guide, we explain FHA loan prequalification, eligibility requirements, necessary documents, credit score considerations, and practical steps to prepare for the mortgage process.
What Does It Mean to Prequalify for an FHA Home Loan?
Prequalifying for an FHA home loan means providing a mortgage lender with basic financial information so they can estimate whether you may qualify for an FHA-backed mortgage.
During this initial process, a lender may ask about your:
- Annual household income.
- Employment history.
- Monthly debt payments.
- Credit score.
- Available savings.
- Estimated down payment.
- Desired home purchase price.
Based on the information you provide, the lender can give you an estimated loan amount and explain whether your financial situation appears suitable for an FHA mortgage.
However, prequalification is not the same as final mortgage approval.
Prequalification is generally an early assessment based on information you provide. A formal mortgage preapproval usually involves a more detailed review of your finances and credit history. Final approval requires additional underwriting, verification, and property-related requirements.
Understanding this difference is important because a prequalification estimate does not guarantee that a lender will approve your mortgage.
What Are the Basic FHA Home Loan Requirements?
Before beginning the prequalification process, familiarize yourself with the main FHA mortgage requirements.
Although individual lenders may apply additional standards, FHA guidelines provide a general framework for evaluating borrowers.
1. Credit Score Requirements
Your credit score is one of the factors lenders consider when reviewing an FHA mortgage application.
Under standard FHA guidelines for eligible borrowers:
- A credit score of 580 or higher generally allows a minimum down payment of 3.5%.
- A credit score between 500 and 579 generally requires a minimum down payment of 10%.
- Borrowers with scores below 500 generally do not qualify under standard FHA minimum requirements.
These are FHA baseline guidelines, not guarantees of lender approval. Many lenders apply their own minimum credit score requirements, which may be higher.
Your credit history also matters. Lenders may review payment patterns, outstanding debts, collections, bankruptcies, and other financial information.
2. Down Payment Requirements
One reason FHA loans attract first-time homebuyers is their relatively low down payment requirement.
Eligible borrowers with credit scores of at least 580 may qualify for a down payment as low as 3.5%.
For example:
- $200,000 home: $7,000 down payment.
- $250,000 home: $8,750 down payment.
- $300,000 home: $10,500 down payment.
- $350,000 home: $12,250 down payment.
Borrowers with credit scores between 500 and 579 generally need at least 10% down.
Your actual cash requirement may be higher because you also need to account for closing costs, prepaid expenses, and other homebuying expenses.
Eligible down payment funds may come from personal savings or approved gift sources, subject to FHA and lender documentation requirements.
3. Income and Employment Requirements
FHA loans do not establish one universal minimum income requirement for every borrower.
Instead, lenders evaluate whether your income is sufficient and reasonably stable to support the proposed mortgage payment.
Common income sources include:
- Full-time employment.
- Part-time employment.
- Self-employment.
- Retirement income.
- Social Security benefits.
- Eligible investment income.
- Other qualifying recurring income.
Lenders generally review your employment history, income consistency, and ability to continue earning.
If you are self-employed, you may need to provide additional financial documents, including tax returns and business income records.
Having a stable income and well-documented employment history can make the qualification process easier.
4. Debt-to-Income Ratio
Your debt-to-income ratio, commonly called DTI, measures how much of your monthly gross income goes toward debt payments.
Lenders use this calculation to evaluate whether you can reasonably manage a new mortgage payment alongside existing financial obligations.
The basic formula is:
DTI = Total Monthly Debt Payments ÷ Gross Monthly Income × 100
For example, suppose your gross monthly income is $6,000 and your monthly debt payments total $2,400.
Your DTI would be:
$2,400 ÷ $6,000 × 100 = 40%.
FHA underwriting generally uses a 31% housing expense ratio and a 43% total debt-to-income ratio as traditional benchmark ratios. However, borrowers may qualify above these figures when permitted by underwriting guidelines and supported by other qualifying factors.
These ratios should not be treated as automatic approval or rejection limits.
5. Primary Residence Requirement
FHA loans are generally intended for people purchasing a home they plan to use as their primary residence.
You typically cannot use a standard FHA purchase loan simply to purchase a vacation property or an investment property.
Eligible property types can include:
- Single-family homes.
- Certain condominiums.
- Eligible two-to-four-unit residential properties.
- Certain manufactured homes.
Additional occupancy, property, and lender requirements may apply.
How to Prequalify for an FHA Home Loan: 7 Steps
Now that you understand the basic requirements, follow these steps to begin your FHA loan prequalification.
Step 1: Check Your Credit Score and Credit Report
Start by reviewing your credit score and credit report before contacting a mortgage lender.
Your credit profile helps determine which FHA financing options may be available to you.
Check for:
- Late payments.
- Outstanding credit card balances.
- Collections.
- Incorrect account information.
- Unpaid debts.
- Recent credit applications.
If you find inaccurate information, consider disputing it with the relevant credit reporting agency.
You can obtain free credit reports through AnnualCreditReport.com.
Avoid applying for several new credit accounts before seeking a mortgage. New accounts and additional debt may affect your credit profile and borrowing capacity.
Step 2: Calculate Your Monthly Income
Next, determine your total gross monthly income.
Include qualifying income from employment and other eligible sources.
For salaried employees, your annual salary can usually be divided by 12 to estimate monthly gross income.
For example, if you earn $72,000 annually:
$72,000 ÷ 12 = $6,000 per month.
If you receive commissions, bonuses, overtime, or self-employment income, the lender may need additional documentation to determine the amount that can be counted.
Use realistic income figures rather than assuming every additional payment will automatically qualify.
Step 3: Calculate Your Existing Monthly Debt
List your current monthly financial obligations.
These may include:
- Auto loan payments.
- Student loan payments.
- Credit card minimum payments.
- Personal loans.
- Existing mortgage payments.
- Other qualifying recurring debts.
Suppose your monthly income is $6,000 and your existing monthly debt payments total $900.
If your estimated new housing payment is $1,500, your total monthly obligations would be $2,400.
Your estimated total DTI would be:
$2,400 ÷ $6,000 × 100 = 40%.
This calculation gives you an initial understanding of how much room you may have for a mortgage payment.
Step 4: Estimate Your Down Payment and Closing Costs
Before requesting FHA loan prequalification, calculate how much money you have available for the purchase.
Remember that the down payment is not your only upfront expense.
You may also need money for:
- Mortgage closing costs.
- Home appraisal.
- Home inspection.
- Property taxes.
- Homeowners insurance.
- Prepaid interest.
- Initial escrow deposits.
Closing costs vary depending on your location, lender, transaction, and loan amount.
Some eligible borrowers may receive assistance through approved down payment assistance programs or seller concessions, subject to applicable FHA limits and lender requirements.
Step 5: Research FHA-Approved Mortgage Lenders
Not every mortgage company offers the same loan options, rates, fees, or qualification standards.
Research lenders that offer FHA financing and compare their services.
Consider asking:
- What minimum credit score do you require?
- Do you offer FHA loans with 3.5% down?
- What documents do you need for prequalification?
- Are there lender-specific qualification requirements?
- What interest rates and fees are currently available?
- Do you offer first-time homebuyer assistance options?
You can also use HUD resources to find FHA-approved lenders.
Comparing multiple lenders can help you understand your options before choosing where to apply.
Step 6: Request FHA Loan Prequalification
Once you have reviewed your finances and identified potential lenders, request an FHA loan prequalification.
The lender may ask you to provide information about:
- Your income.
- Employment.
- Credit history.
- Existing debts.
- Available savings.
- Expected purchase price.
Some lenders offer online prequalification tools, while others conduct the initial assessment over the phone or through a mortgage specialist.
Depending on the lender, prequalification may involve a soft or hard credit inquiry. Ask which type will be used before proceeding.
After reviewing your information, the lender may provide an estimated loan amount and explain whether you appear to meet its initial qualification requirements.
Step 7: Review Your Prequalification Results
Once you receive your estimated borrowing amount, review the results carefully.
Do not automatically assume that the maximum loan amount is the best option for your financial situation.
Consider whether the estimated mortgage payment fits comfortably within your monthly budget.
Your housing expenses may include:
- Principal and interest.
- Property taxes.
- Homeowners insurance.
- FHA mortgage insurance.
- Homeowners association fees, if applicable.
Choose a purchase price that leaves enough room for utilities, maintenance, savings, and everyday expenses.
If the estimated payment seems too high, ask the lender about reducing your target purchase price or improving your financial profile before applying for formal preapproval.
What Documents Do You Need to Prequalify for an FHA Loan?
The initial prequalification process may require only basic financial information. However, a lender may request additional documentation during preapproval and underwriting.
Common documents include:
| Document | Why Lenders Need It |
|---|---|
| Government-issued ID | Identity verification |
| Recent pay stubs | Income verification |
| W-2 forms | Employment income history |
| Federal tax returns | Income and tax verification |
| Bank statements | Savings and available funds |
| Employment information | Employment verification |
| Credit report | Credit history assessment |
| Debt information | Debt-to-income calculation |
Self-employed borrowers may also need business tax returns, profit-and-loss statements, and other financial records.
Prepare these documents early so you can respond quickly when the lender requests them.
What Is the Difference Between FHA Prequalification and Preapproval?
Although the terms are sometimes used interchangeably, prequalification and preapproval are not necessarily the same.
| FHA Prequalification | FHA Preapproval |
|---|---|
| Usually an initial assessment | More detailed financial review |
| May rely on borrower-provided information | Generally involves income and asset verification |
| May involve a soft or hard credit check | Commonly involves a credit review |
| Provides an estimated borrowing amount | Provides a more informed preliminary lending decision |
| Does not guarantee approval | Does not guarantee final approval |
If you are just beginning to explore homeownership, prequalification can help you understand your potential borrowing capacity.
If you are ready to make offers on homes, a lender’s preapproval process is generally more useful.
Final mortgage approval still depends on underwriting, property eligibility, appraisal, and verification of your financial information.
How Much House Can You Afford With an FHA Loan?
The amount you can afford depends on your income, existing debts, credit profile, down payment, interest rate, and other housing expenses.
For example, consider a buyer with:
- Gross monthly income: $6,000.
- Existing monthly debt: $500.
- Estimated housing payment: $1,600.
Total monthly obligations would be $2,100.
The estimated DTI would be:
$2,100 ÷ $6,000 × 100 = 35%.
This is a useful starting calculation, but the lender will also consider FHA underwriting requirements and other financial factors.
Remember that an affordable mortgage payment should leave enough money for emergency savings, home maintenance, utilities, transportation, and other living expenses.
Common Mistakes to Avoid During FHA Loan Prequalification
Even if you meet the basic FHA requirements, certain financial decisions can complicate your mortgage application.
Avoid these common mistakes:
Applying for Multiple New Credit Accounts
Opening several credit cards or taking out new loans can increase your monthly debt obligations and affect your credit profile.
Making Large Undocumented Deposits
Lenders may ask you to explain large deposits into your bank account. Keep documentation showing where the funds came from.
Changing Jobs Without Understanding the Impact
Changing employment does not automatically disqualify you, but changes in income structure or employment stability may require additional review.
Underestimating Closing Costs
Having enough money for the down payment does not necessarily mean you have enough to complete the purchase.
Ignoring Existing Debt
Outstanding loans and credit card payments can reduce the amount a lender is willing to approve.
Choosing the Maximum Loan Amount
Just because a lender estimates that you can borrow a particular amount does not mean that borrowing the maximum is financially comfortable.
Frequently Asked Questions
1. Can I Prequalify for an FHA Loan With a 580 Credit Score?
Yes. Under standard FHA guidelines, eligible borrowers with credit scores of at least 580 may qualify for a minimum down payment of 3.5%. However, individual lenders may impose higher credit score requirements.
2. How Much Income Do I Need to Qualify for an FHA Loan?
There is no universal minimum income requirement for FHA loans. Lenders evaluate your income, existing debt, proposed mortgage payment, and ability to repay the loan.
3. Does FHA Prequalification Affect My Credit Score?
It depends on the lender and the type of credit inquiry used. Some lenders offer prequalification using a soft credit check, while others may perform a hard inquiry. Ask before authorizing a credit check.
4. Can First-Time Homebuyers Get FHA Loans?
Yes. FHA loans are available to eligible first-time and repeat homebuyers. You do not generally need to be a first-time buyer to use an FHA purchase mortgage.
5. How Long Does FHA Loan Prequalification Take?
Some lenders can provide an initial prequalification estimate within minutes or the same day. More detailed reviews may take longer depending on the documents required and the lender’s process.
6. Can I Get an FHA Loan With Existing Debt?
Yes. Having existing debt does not automatically prevent you from qualifying. Lenders evaluate your total debt-to-income ratio and other financial factors to determine whether the mortgage is affordable.
7. Does FHA Prequalification Guarantee Mortgage Approval?
No. Prequalification is an initial assessment, not a final lending decision. You must complete the lender’s application, verification, underwriting, and property requirements before receiving final approval.
8. Do FHA Loans Require Mortgage Insurance?
Yes. FHA loans generally require an upfront mortgage insurance premium and an annual mortgage insurance premium paid in monthly installments. The applicable amounts and duration depend on the loan terms and FHA rules.
Final Thoughts
Learning how to prequalify for an FHA home loan is an important first step toward purchasing a home.
The process helps you understand your financial position, estimate your borrowing capacity, and identify potential qualification issues before committing to a property.
Start by checking your credit report, calculating your monthly income and debt, reviewing your available savings, and researching FHA-approved lenders. Once you understand your financial situation, request prequalification and discuss your options with a mortgage professional.
Remember that prequalification is only an estimate. Final approval depends on a complete review of your finances, applicable FHA requirements, and the property you intend to purchase.
With proper preparation and a realistic budget, you can approach the homebuying process with greater confidence and make informed decisions about your future home.
Read More: