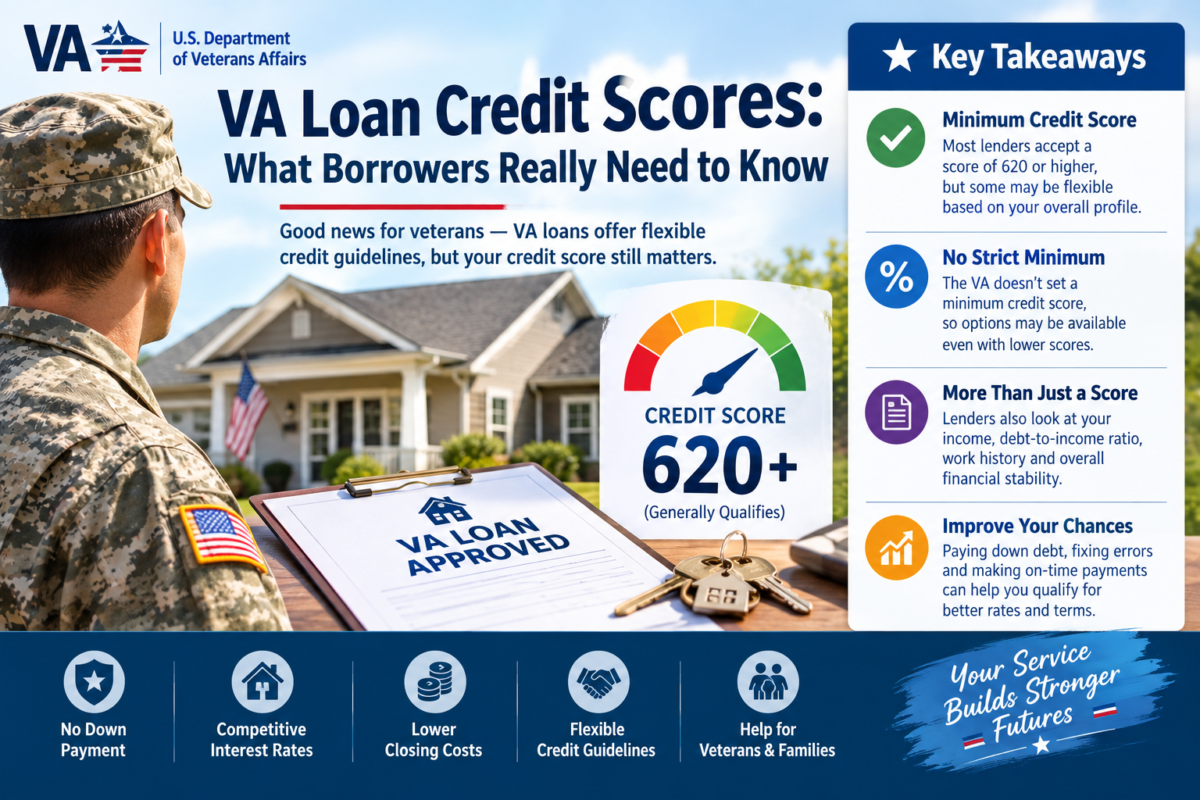
VA Loan Credit Scores: What Borrowers Really Need to Know
October 28, 2026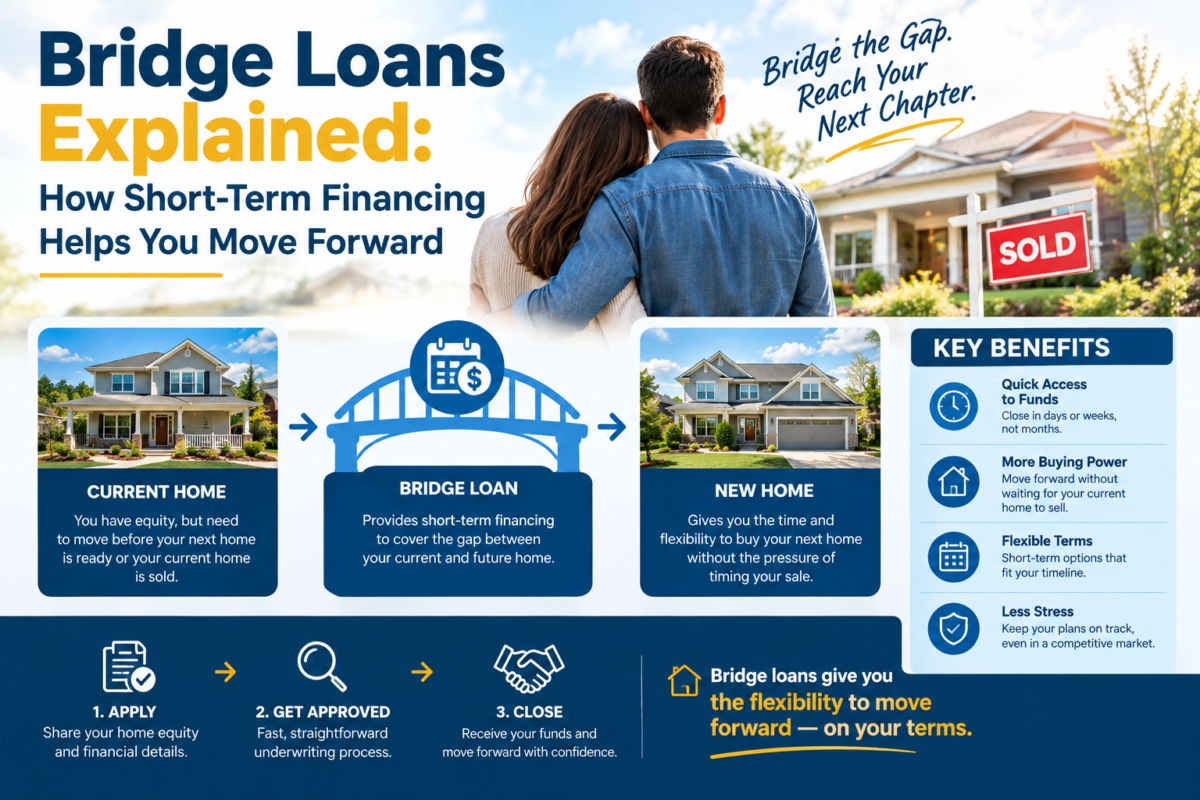
A bridge loan is temporary financing designed to cover a short-term funding gap. It provides money when an expense or purchase must be handled before longer-term financing, sale proceeds, or another expected source of funds becomes available. The term “bridge” describes this role: the loan connects a borrower’s current financial position with a later event expected to provide the funds needed to repay it. For anyone asking “what is a bridge loan,” the central idea is short-term access to capital, rather than permanent financing.
For example, a homeowner may use a bridge loan to buy a new property before selling an existing one. A business might use one to meet operating costs while awaiting a planned investment or a longer-term loan. In real estate, these loans are commonly secured by property, such as the home being sold or the property being purchased. Depending on the transaction, a lender may instead accept other assets as collateral. Security can give the lender a claim against the pledged asset if the borrower does not meet the repayment terms.
Bridge loans are not a single standardized product. Their availability, costs, repayment schedules, eligibility requirements, and permitted uses vary according to the lender, borrower, transaction, and jurisdiction. Some are structured for a few months, while others may allow a longer period; the loan agreement sets the actual term. Borrowers generally need a credible plan for repaying the balance, such as completing a property sale, securing permanent financing, or receiving an expected payment. Because the funding is temporary, it is important to understand when repayment is due and what happens if the anticipated funds arrive late or do not materialize. A bridge loan can help manage timing, but it does not remove the underlying obligation to repay borrowed money.
A bridge loan begins with a specific, near-term funding need and a clear plan for addressing it. A borrower may need to complete a property purchase before selling an existing home, cover expenses while arranging longer-term business financing, or access capital during another temporary gap. Because this financing is intended to be short-term, the application typically focuses on the amount required, the expected timeline, the borrower’s ability to meet payments, and the source that will ultimately repay the debt. Understanding what is a bridge loan includes recognizing that it is structured around this temporary financing gap rather than as a permanent solution.
After identifying the need, the borrower applies with a lender and provides financial information and details about the intended use of the funds. Requirements vary by lender and by the borrower’s circumstances. Some bridge loans are secured by collateral, such as real estate or business assets, while others may rely on different underwriting criteria. When collateral is required, the lender assesses its value and may consider existing debts or claims against it. The borrower should review the interest rate, fees, repayment schedule, maturity date, and any conditions that apply before accepting an offer.
Once the lender approves the application and completes any required checks, funds are released according to the loan agreement. The borrower then uses the proceeds for the stated purpose while arranging the planned repayment source. Common exit strategies include proceeds from selling a property, funds from a permanent mortgage, or approved business financing. The lender may expect repayment in a lump sum when that source becomes available, although payment structures differ. The timeline and conditions should be confirmed in writing so the borrower can coordinate the loan with the expected transaction.
A defined exit strategy is central to the arrangement, but an expected sale, refinance, or financing approval is not guaranteed. Before borrowing, consider what would happen if the repayment source is delayed or does not materialize. A property could take longer to sell, a permanent loan application could be declined, or business funding could arrive later than planned. The borrower should assess available alternatives, the cost of extending or replacing the loan, and the consequences of missing the maturity date. This planning helps clarify whether the short-term financing remains manageable under less favorable circumstances.
Bridge financing is used when a borrower needs funds before longer-term financing or an expected sale can be completed. A common residential example is buying a new home before selling an existing one. The short-term loan can help cover the purchase price or down payment, allowing the buyer to make an offer without waiting for the current property to sell. Repayment may depend on the home sale, so timing and the possibility of a delayed sale are important considerations.
Another use is securing a property while permanent financing is being arranged. An investor or buyer may need to act quickly to meet a transaction deadline, while a mortgage, construction loan, or other long-term funding is still under review. Bridge funds can cover the interim period, but borrowers should understand the cost and conditions of the eventual refinancing.
Property owners and investors may also use short-term financing to fund renovations, repairs, or improvements before a sale or refinance. In some cases, the work may increase a property’s value or make it eligible for permanent financing. Approval can depend on the property, the borrower’s repayment plan, and the expected project timeline.
Businesses may use bridge loans to manage temporary cash-flow gaps or meet transaction needs, such as covering expenses while waiting for receivables, completing an acquisition, or funding a time-sensitive opportunity. These loans may be secured by business assets, real estate, or other collateral, depending on the lender and arrangement.
The term covers distinct products rather than one standard loan. Residential bridge loans commonly support home purchases and may rely on existing or newly purchased housing as collateral. Commercial real estate bridge loans are typically tied to income-producing or investment property and may bridge a purchase, renovation, or transition to permanent financing. Business bridge loans address company funding needs and can involve different underwriting criteria and security. People asking what is a bridge loan should therefore consider the category: eligibility, collateral, repayment structure, costs, and available loan terms can vary substantially.
Bridge loans are designed for short-term financing, so repayment periods are typically measured in months rather than decades. Many arrangements run for several months to around a year, but this is not a universal standard: the term may depend on the lender, the property or transaction, and the borrower’s planned exit strategy. Some lenders may offer extensions, while others impose additional costs or require repayment by a fixed maturity date. Before borrowing, confirm the exact term, extension conditions, and consequences of a late or incomplete repayment.
The interest rate is only one part of the borrowing cost. Because bridge financing is temporary and may involve greater uncertainty than a conventional mortgage, its pricing can differ substantially across lenders and transactions. Borrowers may also pay an origination or arrangement fee, along with appraisal, valuation, legal, title, or other closing costs. Depending on the agreement, there may be an exit fee or a prepayment charge if the loan is repaid early. Ask for a written breakdown of all charges, including when each fee is due and whether it is calculated as a fixed amount or a percentage of the loan.
Repayment structures also affect both monthly cash flow and the total amount due. Some bridge loans require interest-only payments during the term, with the principal repaid in a lump sum at maturity. Others may defer some or all payments until the balance becomes due, which can reduce interim outlays but leave a larger final payment. Clarify whether interest accrues on the full principal, how often it is charged, and what happens if the expected sale, refinance, or other repayment source is delayed. When assessing what is a bridge loan in practical terms, compare the total projected cost across offers—not simply the headline rate. Include fees, payment timing, likely term, and any extension or early-repayment costs, then check that the repayment plan remains workable if circumstances change.
Lenders assessing a bridge loan typically review both the borrower and the asset supporting the financing. Credit history can indicate how reliably an applicant has managed previous obligations, while income or business cash flow helps show whether scheduled payments are affordable during the loan term. Lenders may also examine existing debts and other financial commitments. Even when an application is primarily asset-based, a strong property or business asset does not automatically remove the need to consider creditworthiness and repayment capacity.
Collateral is another central part of underwriting. A lender may assess the property’s market value, condition, location, and potential costs for repairs or improvements. The borrower’s equity in the collateral and the loan-to-value ratio—the loan amount compared with the appraised value—can affect approval, pricing, and the amount available. A lower loan-to-value ratio may provide the lender with a larger equity cushion if repayment does not proceed as planned. Valuations and inspections may be required, depending on the asset and lender.
The proposed repayment plan, often called the exit strategy, is especially important because bridge financing is short term. Applicants may need to explain how they expect to repay the balance, such as through a property sale, refinancing, or proceeds from another transaction. Some lenders place substantial emphasis on collateral and the credibility of this plan, but that emphasis does not mean credit or affordability can be ignored. Borrowers should be prepared to document income, assets, debts, ownership, property details, and the expected source and timing of repayment. Requirements differ: documentation, underwriting standards, valuation methods, and approval timelines vary by lender, loan size, jurisdiction, and transaction. Asking what is a bridge loan in practical terms therefore includes understanding which evidence a particular lender needs and how it will evaluate the borrower’s ability to meet payments as well as the final repayment obligation.
One potential advantage of a bridge loan is access to funds on a tighter timeline than some long-term financing options may allow. When a borrower needs to cover a temporary funding gap, a shorter-term loan may provide a way to proceed while a longer-term loan, property sale, or other source of funds is still being arranged. This can be relevant in real estate transactions, where timing may affect whether a buyer can make an offer or meet a seller’s preferred closing schedule. However, faster access is not guaranteed: application review, underwriting, documentation, and funding times vary by lender and by the complexity of the transaction.
Bridge financing may also help a borrower act before another transaction closes. For example, a homeowner might seek funds to purchase a new property before receiving proceeds from the sale of an existing one. A business may use temporary financing to manage a short-term cash-flow need while waiting for expected revenue or longer-term funding. In these situations, the loan can help connect two stages of a financial plan rather than replace permanent financing. Understanding what is a bridge loan includes recognizing that repayment is generally expected from a defined future source, so borrowers need to consider whether that source is realistic and timely.
Another possible benefit is flexibility for temporary financing needs. Depending on the lender, loan structure, and borrower’s circumstances, funds may support a purchase, renovation, operating expense, or another short-lived requirement. This flexibility can create room to pursue an opportunity that might otherwise be delayed or missed, such as acquiring a property or responding to a business need while conventional financing is pending. Still, a bridge loan is not suitable for every situation. Interest rates, fees, repayment terms, collateral requirements, and the risks of delays should be assessed carefully. Approval speed and suitability depend on the borrower’s financial profile, the transaction, and the lender’s criteria; comparing alternatives and planning for repayment can help determine whether this short-term option fits the need.
Bridge financing can help borrowers act before long-term funding or a property sale is complete, but that flexibility often comes at a price. Interest rates, origination fees, appraisal charges, and other closing costs may be higher than those associated with conventional long-term loans. Because the loan is designed for a brief period, these costs can weigh heavily when measured over a few months. Borrowers considering what is a bridge loan should also examine the full repayment amount and any fees for extending or paying off the loan early.
The short repayment deadline creates another significant limitation. A sale may take longer than expected, or a buyer’s financing, inspection, or closing may be delayed. Refinancing is not guaranteed either: interest rates may rise, lending standards may tighten, or the borrower’s financial circumstances may change before an application is approved. If the loan cannot be repaid on time, default may lead to additional fees, legal action, or foreclosure. Since property or another valuable asset may secure the debt, failure to repay can put that pledged collateral at risk.
An exit plan based on uncertain future events deserves careful scrutiny. A borrower who expects to sell a home for a particular price could receive lower offers, face repairs, or encounter a slower market. Meanwhile, carrying a current mortgage, a new housing payment, and bridge-loan debt can strain monthly cash flow; other outstanding debts may make that pressure more difficult to manage. Before proceeding, test the budget against realistic setbacks: a sale delayed by several months, lower net proceeds after costs, and refinancing offered on less favorable terms. Confirm that accessible savings or another dependable repayment source could cover the gap. A plan that works only if every transaction happens on schedule may leave little room to respond when circumstances change. Compare the total borrowing cost with alternatives, review the loan agreement’s default and extension provisions, and seek qualified financial or legal advice where needed. Understanding these limits helps borrowers judge whether short-term financing suits their circumstances rather than relying on the hoped-for outcome alone.
When considering what is a bridge loan, compare its speed and short repayment period with financing that may cost less. A home equity loan or home equity line of credit can provide funds against an existing property, often at a lower rate, but approval and setup may take time, and the property serves as collateral. These options may suit borrowers with substantial equity and a flexible deadline. A personal loan does not require home collateral and may be quicker to arrange, but borrowing limits can be lower and interest rates higher, particularly for large amounts.
A conventional mortgage may be more appropriate when buying a home without needing to borrow temporarily against another asset. Its application and closing process can be longer, but the repayment schedule is generally designed for long-term affordability. For business needs, a business line of credit may offer reusable access to funds, provided the borrower qualifies and can meet the lender’s terms. It may be a better fit for recurring cash-flow gaps than a one-time property purchase, though limits, fees, and collateral requirements vary. Compare each option’s approval timeline with the date funds are actually needed.
Waiting until the existing property or other asset is sold avoids taking on interim debt and its associated interest, fees, and repayment pressure. That approach may not work if a purchase or business expense cannot be delayed, or if a sale is uncertain. The best comparison depends on timing, available equity, the amount required, collateral, repayment capacity, and total cost—not simply the advertised interest rate. Include closing charges, ongoing fees, and the consequences of a delayed sale in your estimates. Before choosing a bridge loan, ask whether a slower or less expensive alternative can meet the same need without creating unacceptable timing or financial risks.
Before seeking a bridge loan, define the funding gap precisely: how much cash is needed, when it must be available, and how long you expect to borrow. Identify the event that will close the gap, such as selling a property, receiving long-term financing, or completing a business transaction. Be specific about the expected repayment source and timing, and consider whether it is dependable. If repayment depends on a sale, estimate a realistic sale price and timeline rather than relying on the best-case outcome. A clear plan helps determine whether short-term financing addresses a temporary need or merely postpones a larger financial problem.
Next, calculate the full cost of borrowing. Review interest, lender and broker fees, legal expenses, appraisal charges, and any prepayment penalties, along with the required payment schedule. Ask how much you will owe if the loan remains outstanding longer than planned. Test a delayed-exit scenario: consider what happens if a property takes longer to sell, refinancing is unavailable, or expected funds arrive late. Determine whether you could continue making payments and meet the final repayment obligation under those conditions. Also review the collateral securing the loan, including the consequences of missed payments or default. Understand which assets may be at risk before you sign.
Compare written offers from multiple reputable lenders, checking the rate, fees, term, repayment provisions, and default clauses rather than focusing only on speed or the advertised interest rate. Read the contract carefully and ask the lender to explain any unclear terms in writing. When the arrangement involves substantial assets, complex terms, or uncertainty about affordability, consult a qualified financial, legal, or mortgage professional. Ask what is a bridge loan only as a starting point; the practical question is whether its cost and risks fit your circumstances. Bridge financing may suit a temporary, well-planned funding gap, but it should not replace a realistic long-term repayment plan.