Understanding Small Business Administration Loan Eligibility: A Practical Qualification Guide
October 12, 2026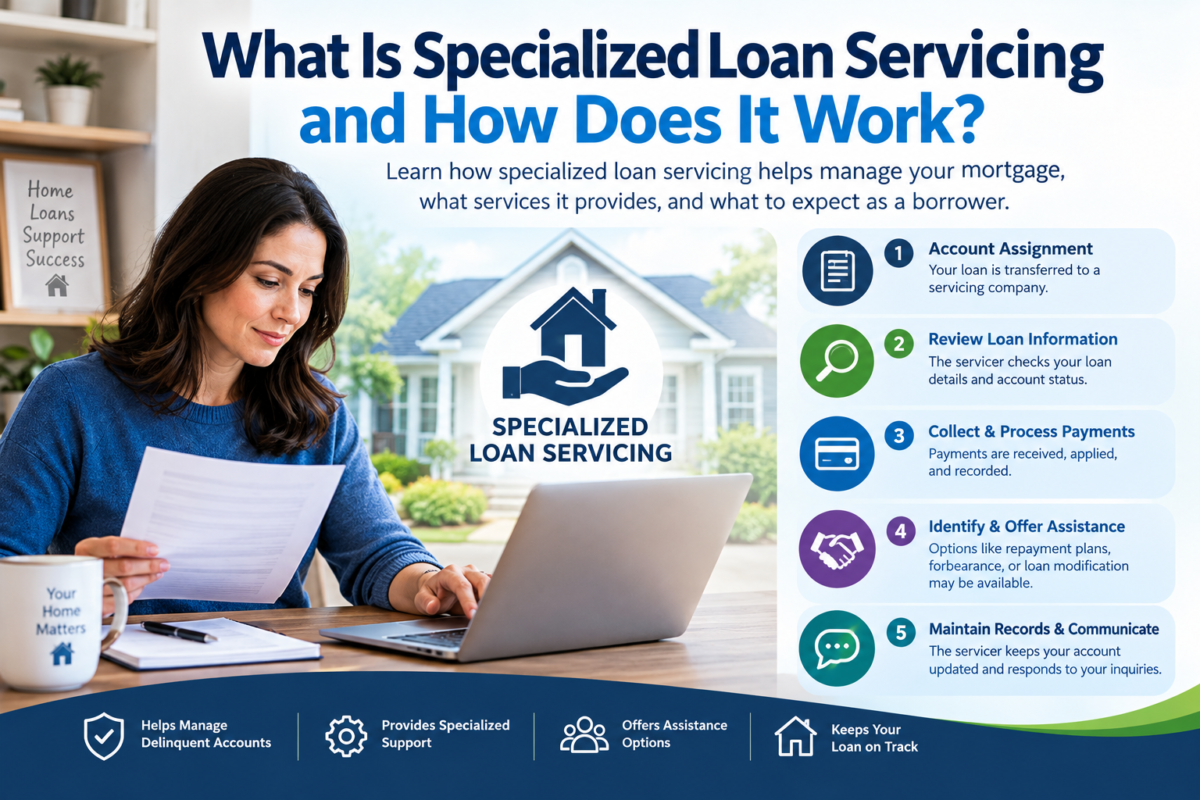
Introduction
Specialized loan servicing plays an important role in the mortgage and lending industry, particularly when borrowers need additional support managing their loan payments or when a loan requires more attention than standard account administration. Understanding what specialized loan servicing is and how it works can help homeowners, borrowers, and investors make informed financial decisions.
When a person takes out a mortgage or another type of loan, the lender does not always manage every aspect of the loan throughout its entire term. In many cases, a separate company called a loan servicer handles routine responsibilities, including collecting monthly payments, maintaining account records, managing escrow accounts, and communicating with borrowers. Some loans require more complex account management, which may involve specialized servicing procedures.
Specialized loan servicing may be used when a mortgage becomes delinquent, a borrower experiences financial difficulties, a loan has unusual terms, or additional attention is needed to manage the account. It can also refer to the work performed by companies that specialize in servicing particular loan portfolios or handling complex mortgage accounts.
This guide explains what specialized loan servicing means, how the process works, the services involved, its benefits and potential drawbacks, and what borrowers should know when working with a loan servicer.
What Is Specialized Loan Servicing?
Specialized loan servicing refers to the management of loans that require particular expertise, additional attention, or procedures beyond routine loan administration. Depending on the context, it may describe specialized servicing operations within the mortgage industry or the services offered by a company that manages mortgage accounts.
Traditional loan servicing generally involves collecting scheduled payments, maintaining account information, issuing statements, and managing escrow payments for property taxes and homeowners insurance. Specialized servicing may involve more complex situations, including delinquent accounts, repayment arrangements, loss mitigation, loan modifications, and certain types of distressed mortgage portfolios.
For example, suppose a homeowner loses a job and cannot make several monthly mortgage payments. The account may require additional communication, an assessment of the homeowner’s financial circumstances, and a review of available options. A servicer handling this situation may need to follow specific procedures for evaluating repayment options and communicating applicable requirements.
It is important to understand that specialized loan servicing is not a single, universally defined loan product. The precise meaning depends on how the term is used by a lender, servicing company, investor, or financial institution.
The term may also refer to a specific business. For example, Specialized Loan Servicing LLC (SLS) is a company in the U.S. mortgage servicing industry. References to this company should not be confused with the general concept of specialized loan servicing.
How Does Specialized Loan Servicing Work?
Specialized loan servicing generally follows a structured process designed to manage a loan account, maintain accurate records, communicate with the borrower, and address issues that arise during repayment. The exact process depends on the loan agreement, servicing arrangement, applicable regulations, and the borrower’s circumstances.
1. Loan Account Assignment
The process begins when a lender, mortgage investor, or another authorized party assigns the servicing responsibilities to a servicing company. A loan may be transferred to a different servicer when a financial institution changes its servicing arrangements or transfers a portfolio of accounts.
The servicer receives relevant account information, which may include:
- The outstanding principal balance.
- The interest rate and repayment terms.
- The borrower’s payment history.
- The current payment schedule.
- Escrow information, if applicable.
- Records of any existing delinquency or repayment arrangement.
The servicer uses this information to establish or maintain the borrower’s account. Borrowers should receive applicable transfer notices explaining where and how to make future payments.
2. Reviewing Loan Information
After receiving the account, the servicer reviews the loan records and confirms the information needed to administer the loan.
This may include verifying the payment amount, due date, interest rate, outstanding balance, escrow requirements, and account status. If the loan has a history of missed payments or an existing assistance arrangement, the servicer may also review relevant records.
Accurate account information is essential because errors involving payment histories, balances, or escrow amounts can create confusion and may affect the handling of a borrower’s account.
3. Collecting and Processing Payments
One of the main responsibilities of a loan servicer is collecting and processing payments. Depending on the loan agreement, payments may include principal, interest, property taxes, homeowners insurance, and other authorized charges.
Borrowers may be able to pay through online portals, automatic bank transfers, telephone systems, mailed checks, or other approved methods.
The servicer records payments and applies them according to the loan terms and applicable requirements. Borrowers should review their statements regularly to confirm that payments are credited correctly.
If a payment is late, incomplete, or missing, the servicer may contact the borrower and explain the account status, applicable charges, and available next steps.
4. Identifying Payment Difficulties
Specialized servicing may become particularly important when a borrower experiences financial hardship or falls behind on payments.
Potential warning signs include repeated missed payments, returned payments, unpaid escrow shortages, or requests for assistance. The servicer may communicate with the borrower to understand the circumstances and explain available procedures.
Financial difficulties can result from job loss, reduced income, medical expenses, divorce, unexpected home repairs, or other changes in a household’s financial situation.
Contacting the servicer early can help borrowers understand their options before the situation becomes more difficult to resolve. However, the availability of assistance depends on the loan, investor requirements, applicable law, and the borrower’s eligibility.
5. Evaluating Available Assistance
Depending on the loan and the borrower’s circumstances, the servicer may explain or evaluate options designed to address payment difficulties.
Possible options may include a repayment plan, forbearance, a loan modification, or another loss mitigation solution. These options have different requirements and financial consequences.
For example, a repayment plan may allow a borrower to pay an overdue amount over time in addition to regular monthly installments. Forbearance may temporarily reduce or suspend payments under an approved agreement, but it generally does not eliminate the amount owed. A loan modification may change certain loan terms to make payments more manageable.
Not every borrower qualifies for every option, and some arrangements require financial documentation and formal approval. Borrowers should request written explanations of the terms before agreeing to a proposed solution.
6. Maintaining Records and Communicating With Borrowers
Loan servicing companies maintain account records, issue statements, process requests, and respond to borrower inquiries. Depending on the account, they may also manage escrow disbursements, send notices, and provide information about payment status.
When a borrower disputes an account balance or believes a payment has not been credited correctly, written communication can help create a clear record of the issue and the steps taken to resolve it.
Borrowers should retain payment confirmations, account statements, correspondence, and copies of any assistance agreements. Good recordkeeping can make it easier to resolve misunderstandings and verify whether the servicer has followed the agreed terms.
What Services Does Specialized Loan Servicing Provide?
The services available vary by company and loan type. Common responsibilities may include the following.
Mortgage Payment Processing
Servicers collect monthly payments, apply funds to the account, maintain transaction histories, and report account balances. They may also provide online access to payment records and account information.
Escrow Account Management
For mortgages with escrow accounts, the servicer may collect funds for property taxes and homeowners insurance and distribute payments when they become due. Escrow calculations can change when taxes or insurance premiums increase or decrease.
Borrowers should review annual escrow statements and contact the servicer if a payment or disbursement appears incorrect.
Delinquency Management
When payments are missed, the servicer monitors the account, communicates with the borrower, and follows applicable procedures for handling delinquency. Depending on the circumstances, this may include explaining overdue amounts and discussing potential assistance options.
Loss Mitigation Support
Loss mitigation refers to efforts to address mortgage delinquency and, where possible, avoid foreclosure. Depending on the loan and applicable rules, a servicer may collect documents, evaluate assistance applications, communicate decisions, and administer an approved arrangement.
Loan Modification Administration
If a modification is approved by the appropriate party, the servicer may update the account to reflect the revised terms and explain the new payment schedule. Borrowers should carefully review the agreement to understand any changes to the interest rate, repayment period, principal balance, or other terms.
Account Inquiries and Documentation
Servicers may respond to requests for payment histories, account statements, payoff information, escrow details, and explanations of account activity. Some requests may have specific submission procedures or response deadlines under applicable law.
Specialized Loan Servicing vs. Traditional Loan Servicing
Both traditional and specialized loan servicing involve administering loan accounts, but they may differ in the complexity of the accounts handled and the procedures required.
Traditional servicing commonly focuses on routine payment collection, account maintenance, escrow administration, and customer service for loans that are being repaid according to schedule.
Specialized servicing may involve more complex account situations, such as delinquency, financial hardship, complicated loan terms, or loans requiring additional monitoring and coordination.
For example, a homeowner who makes every mortgage payment on time may mainly interact with a servicer to review statements and manage automatic payments. A homeowner who has missed several payments may need more detailed communication, document reviews, and an assessment of possible repayment or loss mitigation arrangements.
These categories are not always separate. A single mortgage servicer may perform routine servicing for some accounts and specialized servicing activities for others.
Who Uses Specialized Loan Servicing?
Specialized loan servicing can be relevant to several groups within the lending industry.
Homeowners Experiencing Financial Hardship
Borrowers who cannot make their mortgage payments may need information about delinquency, repayment options, or loss mitigation. A servicer can explain the applicable process and identify the documentation needed to evaluate a request.
Borrowers With Complex Loan Arrangements
Some loans have terms, payment structures, or account requirements that demand additional administrative attention. Specialized servicing may help manage these requirements and maintain accurate records.
Mortgage Lenders and Investors
Lenders and investors may use servicing companies to administer loan portfolios, process payments, maintain account data, and handle accounts that require additional oversight.
Financial Institutions Managing Delinquent Loans
Institutions with loans that are behind on payments may rely on specialized servicing expertise to manage communications, review eligible assistance options, and follow the applicable procedures for resolving delinquency.
Benefits of Specialized Loan Servicing
Specialized loan servicing can provide several potential benefits when an account requires additional attention.
1. More Focused Account Management
Accounts involving complex repayment issues may require closer monitoring than routine mortgages. Specialized procedures can help organize account information, track required documents, and manage communications.
2. Access to Information About Assistance Options
Borrowers who experience financial hardship may benefit from clear explanations of the options available under their loan and applicable requirements. Although a servicer cannot guarantee approval, it can explain the process for requesting assistance.
3. Organized Payment and Account Records
Accurate records help borrowers and servicers track payments, outstanding balances, escrow transactions, and changes to loan terms. This information is particularly important when an account has a history of missed payments or disputed transactions.
4. Support for Lenders and Investors
Outsourcing servicing responsibilities can allow lenders and investors to rely on companies with systems and experience for administering loan portfolios. This may help them manage operational demands and monitor account performance.
5. Structured Handling of Delinquent Accounts
A defined process for reviewing overdue payments, communicating with borrowers, and evaluating available options can help make account management more consistent. The result depends on the quality of the servicer, the borrower’s circumstances, and applicable requirements.
Potential Drawbacks and Challenges
Specialized loan servicing can also create challenges for borrowers.
Confusion During a Servicing Transfer
When a mortgage transfers from one servicer to another, borrowers may need to update payment instructions, register for a new online account, or confirm where to send correspondence. Transfer notices and applicable payment-transfer protections are important.
Communication Delays
Borrowers may become frustrated if they have difficulty reaching the appropriate department, receiving updates, or understanding the status of a request. Keeping records of telephone calls, dates, reference numbers, and written correspondence can help.
Account Errors
Incorrect payment applications, inaccurate balances, or escrow calculation problems can occur. Borrowers should review statements and raise concerns promptly through the servicer’s established dispute or inquiry process.
Limited Eligibility for Assistance
Specialized servicing does not mean that every borrower will qualify for a loan modification, forbearance, or repayment plan. Approval depends on the specific program, investor requirements, financial information, and other eligibility criteria.
Additional Stress During Financial Hardship
Managing a mortgage problem can be stressful, especially when a borrower is already experiencing financial difficulties. Understanding the available options and obtaining written explanations can help borrowers make more informed decisions.
What Should Borrowers Know About Specialized Loan Servicing LLC?
Specialized Loan Servicing LLC, commonly known as SLS, is a U.S. mortgage servicing company. Borrowers who receive a notice naming SLS should confirm that the notice is legitimate and review the instructions carefully.
If SLS services your mortgage, you may use the contact information and account access methods listed on your official servicing statements or its verified website to review payment details, submit requests, or ask questions about your loan.
A servicing company does not necessarily own the mortgage it administers. The mortgage owner or investor may be a different organization, while the servicer manages account administration on its behalf.
If you receive a mortgage servicing transfer notice, verify the effective date, the new payment address or online payment method, and any instructions about automatic payments. Do not rely on an unexpected email or text message without independently verifying its authenticity.
For company-specific questions about SLS, use official company resources rather than assuming that every general explanation of specialized servicing describes its particular policies or procedures.
What Are Borrowers’ Rights When Working With a Loan Servicer?
Mortgage borrowers in the United States have certain rights under federal law, including applicable provisions of the Real Estate Settlement Procedures Act (RESPA) and Regulation X. The specific protections depend on the circumstances and the type of loan.
For covered mortgages, borrowers may have the right to submit a written request for information or a notice of error to the servicer’s designated address. The servicer generally must follow applicable acknowledgment and response deadlines, subject to regulatory exceptions.
Federal mortgage servicing rules also establish requirements for certain loss mitigation procedures, account communications, and foreclosure-related activities. These requirements are not identical for every loan or situation.
Borrowers should:
- Review mortgage statements and servicing notices carefully.
- Keep copies of payment confirmations and written communications.
- Ask for clarification when a balance or fee appears incorrect.
- Submit disputes or information requests using the required procedures.
- Request written details of any repayment plan or loan modification.
- Seek qualified housing counseling or legal advice if facing possible foreclosure.
The Consumer Financial Protection Bureau (CFPB) provides information about mortgage servicing and consumer complaint options. Borrowers can visit the CFPB website to learn more about their rights and potential next steps.
How to Handle Problems With a Specialized Loan Servicer
If you believe your servicer has made an error or failed to respond to a request, start by gathering relevant records. These may include mortgage statements, bank payment confirmations, correspondence, and any agreement affecting your payment obligations.
Next, contact the servicer through an official channel and clearly explain the issue. Ask what documents are required and how the matter will be reviewed. If the problem involves a disputed payment, incorrect fee, or inaccurate balance, provide supporting evidence.
For issues that remain unresolved, consider submitting a formal written notice of error or request for information, when applicable, using the address and procedures specified by the servicer. You may also submit a complaint to the CFPB or seek assistance from a qualified housing counselor or attorney.
If you receive a foreclosure notice, do not ignore it. Deadlines may be important, and a complaint or assistance request does not automatically stop foreclosure proceedings. Seek qualified legal help promptly if you need advice about your rights or options.
Tips for Managing Your Loan Servicing Account
Managing a loan account carefully can help prevent avoidable problems and make communication with the servicer easier.
Set up payment reminders. Use calendar alerts or automatic payments if appropriate for your circumstances. Check that payments have been processed successfully.
Review statements regularly. Confirm that the payment amount, outstanding balance, fees, and escrow activity appear accurate.
Keep contact information current. Make sure your servicer has your correct mailing address, telephone number, and email address.
Save important documents. Retain account statements, transfer notices, payment confirmations, and written agreements in a secure location.
Contact the servicer early. If you expect difficulty making a payment, ask about available options before the account becomes significantly overdue.
Verify unexpected requests. Confirm changes to payment instructions directly through an official website or verified telephone number before sending money or sharing sensitive information.
Conclusion
Specialized loan servicing refers to loan administration that requires particular expertise, additional oversight, or procedures beyond routine payment processing. It may involve managing delinquent mortgages, reviewing borrower assistance requests, maintaining complex account records, administering loan modifications, and communicating with borrowers about their obligations.
For homeowners, understanding how specialized loan servicing works can make it easier to manage mortgage payments, identify account errors, respond to servicing transfers, and explore available assistance during financial hardship. For lenders and investors, specialized servicing can provide operational support for managing complex loan portfolios.
The most important step for borrowers is to understand who services their loan, review account statements regularly, keep accurate records, and communicate promptly when problems arise. If you are facing delinquency or possible foreclosure, learn about your available options and seek qualified assistance rather than assuming that a servicing company can automatically change your loan terms.
By staying informed about the servicing process and understanding your rights, you can make better decisions and manage your loan account with greater confidence.
Frequently Asked Questions (FAQs)
1. What is specialized loan servicing?
Specialized loan servicing refers to managing loans that require additional attention, expertise, or procedures beyond routine loan administration. It may include delinquency management, loss mitigation, complex account administration, and borrower assistance.
2. How does specialized loan servicing work?
A servicer maintains the loan account, processes payments, reviews account information, communicates with the borrower, and handles issues according to the loan agreement and applicable rules. If the borrower experiences financial hardship, the servicer may explain or evaluate available assistance options.
3. Is Specialized Loan Servicing LLC a lender?
Specialized Loan Servicing LLC is a mortgage servicing company. A servicer administers mortgage accounts and does not necessarily own the loans it manages or provide new loans directly.
4. Can specialized loan servicing help if I miss mortgage payments?
A servicer can explain your account status and the process for requesting assistance. Depending on your circumstances and eligibility, options may include a repayment plan, forbearance, or loan modification. Approval is not guaranteed.
5. Does specialized loan servicing charge borrowers additional fees?
Fees depend on the loan agreement, the services involved, and applicable law. Borrowers should review their mortgage documents and statements and ask the servicer to explain any unfamiliar or disputed charges.
6. What should I do if my loan servicing company changes?
Read the servicing transfer notice, confirm the effective date and new payment instructions, and verify any automatic payment arrangements. Keep the notice and payment records, and contact the new servicer through verified channels if you have questions.
7. How can I dispute an error made by my loan servicer?
Review your records and contact the servicer through its official dispute or inquiry process. For covered mortgages, you may be able to submit a formal notice of error or request for information under applicable federal rules.
8. Can a specialized loan servicer foreclose on my home?
A servicer may carry out foreclosure-related activities on behalf of the mortgage owner when legally authorized and when applicable requirements are met. Borrowers facing foreclosure should review all notices carefully and seek qualified legal assistance promptly.
9. Is specialized loan servicing the same as loan modification?
No. Loan servicing is the administration of a loan account, while a loan modification changes certain loan terms under an approved agreement. A servicer may administer a modification, but it does not mean every borrower will qualify.
10. Where can I get help with a mortgage servicing problem?
You can contact your servicer, consult a qualified housing counselor, or visit the Consumer Financial Protection Bureau website for information about mortgage servicing and complaint options. If foreclosure or a legal dispute is involved, consider consulting a qualified attorney.
Read More: