What Is Specialized Loan Servicing and How Does It Work?
October 13, 2026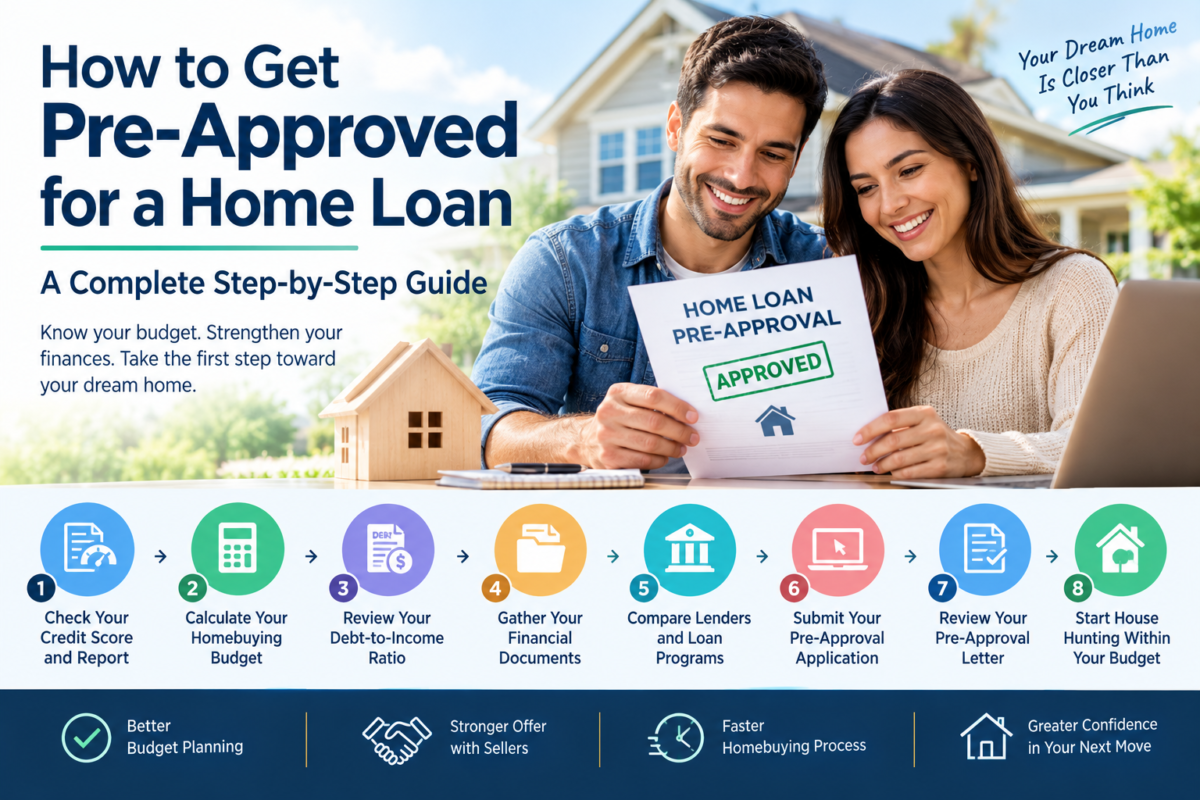
Buying a home is an important financial decision, and understanding how to get pre-approved for a home loan is one of the first steps toward becoming a homeowner. A mortgage pre-approval helps you understand how much a lender may be willing to lend, estimate your purchasing budget, and demonstrate to sellers that you are a serious buyer.
Whether you are purchasing your first home, moving to a larger property, or buying a house after renting, preparing for mortgage pre-approval can make the homebuying process more organized. Lenders generally evaluate your income, credit history, existing debts, savings, and other financial details before issuing a pre-approval letter.
However, pre-approval does not guarantee final mortgage approval. Your loan will usually require further verification, and the property itself must satisfy the lender’s requirements.
This guide explains how to get pre-approved for a home loan in the United States, which documents you need, how credit scores and debt affect eligibility, and how to improve your chances of obtaining a mortgage that fits your budget.
What Does It Mean to Get Pre-Approved for a Home Loan?
A home loan pre-approval is a preliminary assessment by a mortgage lender indicating that you may qualify to borrow up to a specified amount based on the financial information reviewed.
During the process, the lender may examine your credit report, income, employment, assets, existing debts, and estimated down payment. The depth of verification varies by lender, so it is important to understand what your pre-approval actually confirms.
A pre-approval letter can help you establish a realistic home-shopping budget and show sellers that you have taken steps toward arranging financing.
For example, if a lender pre-approves you for a mortgage of $300,000, that does not necessarily mean you should purchase the most expensive home available at that borrowing level. You still need to consider property taxes, homeowners insurance, maintenance, utilities, closing costs, and your other financial obligations.
The Consumer Financial Protection Bureau explains that pre-approval is not a guaranteed loan offer and that letters commonly expire after a limited period, often around 30 to 60 days.
Pre-Approval vs. Prequalification: What Is the Difference?
Homebuyers often confuse mortgage pre-approval with prequalification. Lenders sometimes use these terms differently, so ask what verification each process includes.
Prequalification: This may be an initial estimate based on information you provide about your income, debts, assets, and credit. Depending on the lender, it may involve limited verification.
Pre-approval: This generally involves a more detailed review of your financial situation and may include a credit check and document verification.
Neither term automatically means that your mortgage is fully approved. Final approval normally depends on additional underwriting, verification, and property-related requirements.
If you are preparing to make an offer on a house, ask for a pre-approval letter that reflects the lender’s actual review process and is suitable for your local housing market.
How to Get Pre-Approved for a Home Loan: 8 Essential Steps
Step 1: Review Your Credit Score and Credit Report
Your credit profile is an important factor in mortgage qualification. Lenders may use credit scores and information from your credit report to assess repayment history, determine eligibility for particular loan programs, and set the interest rate offered.
Before applying, obtain your credit reports and review them for errors, unfamiliar accounts, incorrect balances, and inaccurate late-payment information. You can check your own credit without creating the type of hard inquiry associated with a lender’s credit application.
If you find errors, dispute them with the relevant credit reporting agency and provide supporting documentation.
If your credit needs improvement, consider paying bills on time, reducing high credit card balances, and avoiding unnecessary new credit applications. Mortgage credit requirements differ by loan type and lender, so there is no single score that guarantees approval for every borrower.
Step 2: Calculate Your Homebuying Budget
Before contacting lenders, estimate the monthly housing payment you can comfortably afford.
Your total housing expense may include:
- Mortgage principal and interest.
- Property taxes.
- Homeowners insurance.
- Mortgage insurance, if applicable.
- Homeowners association fees, where applicable.
- Maintenance and repair expenses.
For example, a mortgage payment that looks manageable by itself may become difficult when property taxes, insurance premiums, utilities, and maintenance are included.
Create a household budget using your take-home income, existing debt payments, savings goals, and regular living expenses. Keep some money available for emergencies rather than committing all your savings to the down payment.
Remember that a lender’s maximum approved amount is not necessarily your ideal spending limit.
Step 3: Check Your Debt-to-Income Ratio
Your debt-to-income ratio, commonly called DTI, compares your monthly debt obligations with your gross monthly income.
A simplified formula is:
DTI = Monthly debt payments ÷ Gross monthly income × 100
For example, suppose your gross monthly income is $6,000 and your qualifying monthly debt obligations total $2,100, including the proposed housing payment.
Your DTI would be 35%.
Lenders use DTI alongside credit, assets, income stability, and other factors. The maximum acceptable ratio depends on the mortgage program and underwriting circumstances.
If your DTI is high, paying down certain debts or considering a less expensive home may improve affordability. Avoid taking on additional monthly obligations before applying for a mortgage.
Step 4: Gather Your Financial Documents
Preparing your paperwork in advance can help reduce delays during the pre-approval process. Exact requirements vary by lender and borrower circumstances.
Commonly requested documents include:
Proof of income
- Recent pay stubs.
- W-2 forms from recent tax years.
- Federal tax returns, where required.
- 1099 forms for applicable contract income.
- Business tax returns and profit-and-loss statements for many self-employed borrowers.
- Documentation of eligible additional income.
Proof of assets
- Checking and savings account statements.
- Investment account statements.
- Retirement account information, where relevant.
- Documentation showing the source of down payment funds.
- Gift letters and supporting records when eligible gift funds are used.
Identification and personal information
- Government-issued photo identification.
- Social Security number or other identification information accepted by the lender.
- Residential address and employment history.
- Information about existing loans and monthly debt payments.
Additional documents may be requested for rental income, child support, alimony, bankruptcy, divorce, or other circumstances.
Fannie Mae provides a useful home loan document checklist that explains common mortgage documentation requirements.
Step 5: Compare Mortgage Lenders and Loan Programs
Do not assume that the first lender you contact will offer the most suitable mortgage.
Compare banks, credit unions, mortgage companies, and other reputable lenders. Depending on your circumstances, you may want to explore conventional mortgages, FHA loans, VA loans for eligible borrowers, or USDA loans for qualifying properties and applicants.
Compare more than the advertised interest rate. Review:
- Annual percentage rate (APR).
- Origination fees and other lender charges.
- Down payment requirements.
- Mortgage insurance costs.
- Available interest-rate options.
- Loan terms and repayment periods.
- Eligibility requirements and processing times.
Ask whether the lender offers a fully documented pre-approval or a preliminary estimate based on unverified information.
Getting pre-approved by more than one lender can help you compare options. When shopping for mortgage credit, ask lenders how their credit inquiries are handled and try to complete comparisons within a focused period, since scoring models may treat multiple mortgage inquiries differently.
Step 6: Submit Your Pre-Approval Application
Once you have selected lenders to approach, complete their application process accurately.
You may be asked to provide your income, employment details, monthly debts, available assets, expected down payment, and permission to check your credit.
Some lenders provide online applications, while others offer assistance through a loan officer or mortgage broker.
Provide consistent, truthful information and respond promptly to requests for additional documents. If your income includes bonuses, commissions, freelance earnings, or self-employment revenue, explain how it is earned and provide the documentation requested.
Incomplete or inconsistent information can delay the review or lead to a lower borrowing estimate than expected.
Step 7: Review the Pre-Approval Letter Carefully
If the lender determines that you may qualify, it can issue a pre-approval letter stating the potential loan amount and any applicable conditions.
Check the letter for:
- The approved or estimated loan amount.
- The type of mortgage being considered.
- The date the letter expires.
- Conditions that must be satisfied.
- Whether the lender has verified your income, assets, and credit.
- Any restrictions that may affect your home search.
Ask the lender what could cause the pre-approval to change or be withdrawn. A job change, new debt, reduced income, or problems with the property can affect final approval.
Only share the information needed with your real estate agent or seller, and ask your lender to issue an updated letter if your budget or offer changes.
Step 8: Start Shopping for a Home Within Your Budget
With a current pre-approval letter, you can begin looking for homes that fit your financial plan.
A real estate agent can help you evaluate properties, understand local pricing, and prepare an offer. In competitive markets, sellers may view pre-approval as evidence that a buyer has taken financing seriously.
Nevertheless, pre-approval does not replace an inspection, appraisal, title review, or final underwriting.
Once you have an accepted offer, the lender will typically review the property details and may request updated financial documents. Continue to respond promptly and keep your finances stable throughout the transaction.
How Much Money Do You Need for Home Loan Pre-Approval?
There is no single amount of savings required for every mortgage pre-approval. Your financial needs depend on the loan program, purchase price, credit profile, closing costs, and lender requirements.
Your available funds may need to cover:
Down payment: This is the amount you contribute toward the home’s purchase price. Some mortgage programs allow relatively small down payments for eligible borrowers.
Closing costs: These may include lender fees, appraisal expenses, title services, prepaid taxes, and insurance-related costs.
Earnest money: In some transactions, buyers deposit funds to demonstrate their intention to complete the purchase. The contract determines how these funds are handled.
Reserves: Some loan programs or lenders may require borrowers to retain funds after closing, depending on the transaction and financial profile.
For example, a buyer purchasing a $250,000 home with a 5% down payment would contribute $12,500 toward the purchase price before accounting for closing costs and other expenses. Actual eligibility and required funds depend on the loan program.
Ask your lender for a written estimate of the cash needed to complete the purchase.
What Can Cause a Home Loan Pre-Approval to Be Denied?
A lender may decline pre-approval or offer a lower borrowing amount for several reasons.
Low or limited credit history: The lender may be unable to establish sufficient creditworthiness under its requirements.
High debt-to-income ratio: Existing debt payments may leave insufficient qualifying income for the proposed mortgage.
Insufficient or unstable documented income: The lender may be unable to verify enough qualifying income to support the requested loan.
Limited down payment funds: The borrower may not have enough eligible funds for the chosen loan program and transaction costs.
Unexplained financial activity: Large deposits or inconsistent account information may require additional documentation.
Recent credit problems: Certain delinquencies, collections, bankruptcies, or other events may affect eligibility, depending on the loan program and circumstances.
If your application is declined, ask the lender for the specific reasons. Review any relevant adverse-action notice, correct report errors if applicable, and consider consulting a HUD-approved housing counselor before applying again.
Common Mistakes to Avoid After Pre-Approval
Getting pre-approved is an important milestone, but your financial situation must remain suitable until closing.
Avoid these common mistakes:
- Opening new credit cards or taking out a car loan without considering the impact on mortgage qualification.
- Making large purchases that reduce your available funds.
- Changing jobs or income arrangements without discussing the effect with your lender.
- Moving large amounts of money without keeping documentation.
- Missing payments on existing credit accounts.
- Assuming the pre-approved amount is the amount you should spend.
- Ignoring property taxes, homeowners insurance, maintenance, and closing costs.
- Assuming pre-approval guarantees the mortgage will close.
If your circumstances change, tell your loan officer promptly. Clear communication can help prevent unexpected problems later in the process.
Frequently Asked Questions About Home Loan Pre-Approval
1. How long does it take to get pre-approved for a home loan?
Some lenders can issue a preliminary decision quickly when information is complete, while a detailed review may take several business days or longer. Timing depends on the lender, documentation, credit review, and complexity of your finances.
2. Does getting pre-approved hurt your credit score?
A lender may use a hard credit inquiry when evaluating your mortgage pre-approval, which can affect your credit score. Checking your own credit report does not create the same type of inquiry. Ask the lender how it will check your credit.
3. How long does a mortgage pre-approval last?
Many pre-approval letters remain valid for approximately 30 to 60 days, although policies vary. If your letter expires before you find a home, the lender may need updated information or a new credit review.
4. Can I get pre-approved with a low credit score?
Possibly. Eligibility depends on the mortgage program, the lender’s requirements, your broader financial profile, and other qualifying factors. Ask about appropriate loan programs and steps that could strengthen your application.
5. Can self-employed borrowers get pre-approved?
Yes. Self-employed borrowers may qualify by documenting eligible income, often through tax returns, business financial statements, and other records requested by the lender. Income calculations may differ from those used for salaried employees.
6. Is pre-approval a guarantee that I will get a mortgage?
No. The lender may still need to verify your finances, assess the property, review the appraisal, and satisfy other underwriting conditions before issuing final approval.
7. Should I get pre-approved before looking at houses?
If you are ready to buy soon, pre-approval can help establish a realistic budget and strengthen an offer. Some buyers begin with general research or prequalification, then obtain a more detailed pre-approval before serious home shopping.
Conclusion
Learning how to get pre-approved for a home loan can make buying a home more manageable. Start by reviewing your credit, calculating an affordable budget, understanding your debt-to-income ratio, and organizing your financial documents.
Next, compare lenders and mortgage programs, complete the application accurately, and review the conditions of your pre-approval letter. Once you begin shopping for a property, keep your finances stable and stay in contact with your lender until the mortgage closes.
A well-prepared pre-approval can help you understand your borrowing options, demonstrate that you are a serious buyer, and move toward homeownership with greater confidence. The best mortgage is not necessarily the largest one available, but the one that supports your long-term financial goals.
Read More: