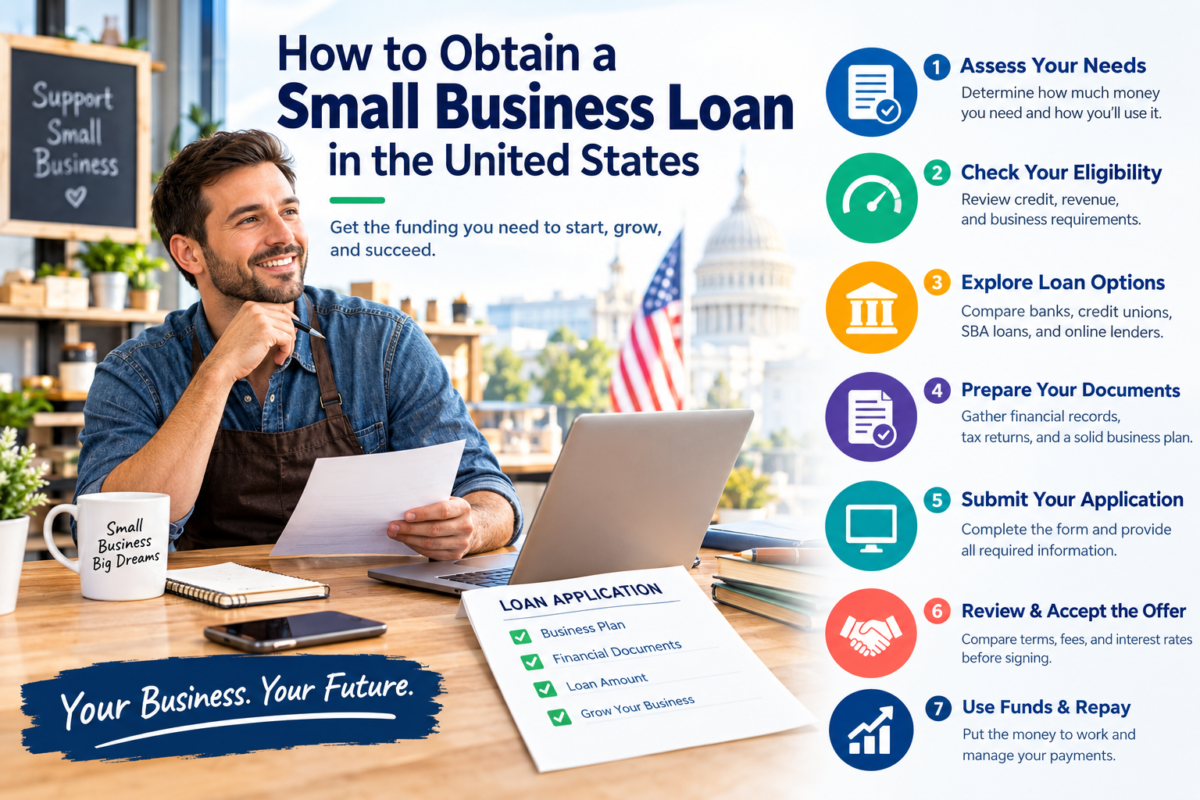
How to Obtain a Small Business Loan in the United States: A Complete Guide
October 19, 2026
Home renovations can make your house more comfortable, improve energy efficiency, increase functionality, and potentially raise its market value. Whether you want to remodel your kitchen, renovate a bathroom, replace an aging roof, finish a basement, or repair structural damage, the cost can add up quickly. If you do not have enough savings to cover the project, a renovation loan may help you pay for the work over time.
Understanding how to get a loan for house renovations starts with choosing the right financing option for your budget, credit profile, home equity, and renovation goals. Some homeowners qualify for personal loans that do not require collateral, while others may benefit from home equity loans, HELOCs, or government-backed renovation mortgage programs.
This guide explains the main ways to finance home improvements in the United States, how to qualify, what lenders consider, and how to avoid common borrowing mistakes.
What Is a House Renovation Loan?
A house renovation loan is financing used to pay for repairs, upgrades, remodeling, or other improvements to a residential property. Depending on the loan type, the money may be provided as a lump sum, made available through a revolving credit line, or incorporated into a mortgage.
Homeowners commonly use renovation financing for:
- Kitchen remodeling and bathroom upgrades
- Roof replacement and structural repairs
- Plumbing, electrical, and HVAC improvements
- Basement finishing and room additions
- Flooring, windows, doors, and insulation
- Accessibility improvements
- Energy-efficient upgrades
- Repairs needed before selling or moving into a home
Not every loan has the same restrictions. Some personal loans allow borrowers to use the proceeds for a wide range of home improvements, while certain mortgage programs require approved contractors, inspections, project documentation, and lender approval.
Before applying, estimate the full cost of the renovation and determine whether you need funds for one project or several improvements.
How to Get a Loan for House Renovations
The process of getting a home renovation loan is usually straightforward when you prepare your financial information and project details in advance.
Step 1: Calculate Your Renovation Budget
Start by identifying the work you want to complete and estimating the cost of materials, labor, permits, inspections, and related expenses. Request written estimates from qualified contractors when possible.
For example, your renovation budget might include:
- Materials and supplies
- Contractor labor
- Building permits and inspection fees
- Temporary accommodation, if needed
- Waste removal and cleanup
- Unexpected repairs
Consider setting aside a contingency reserve for unforeseen expenses. The appropriate amount depends on the property’s condition and the project’s complexity; older homes and structural renovations may need a larger reserve.
Borrowing more than necessary can increase interest costs, so use a realistic project budget rather than choosing a loan amount based only on what a lender offers.
Step 2: Review Your Credit Score and Credit History
Your credit profile can affect your eligibility, interest rate, loan amount, and repayment terms. Lenders may review your payment history, outstanding debt, credit utilization, and recent applications for credit.
Before applying, check your credit reports for inaccurate information. If possible, pay down high-interest revolving debt, make payments on time, and avoid taking on unnecessary new debt.
A lower credit score does not automatically prevent you from obtaining renovation financing. However, it may limit your choices or result in a higher interest rate. Compare offers carefully instead of accepting the first approval you receive.
Step 3: Calculate Your Debt-to-Income Ratio
Your debt-to-income ratio, commonly called DTI, compares your monthly debt obligations with your gross monthly income.
For example, if you earn $6,000 per month before taxes and pay $1,800 toward monthly debts, your DTI is 30%.
[
\text{DTI}=\frac{\text{Monthly debt payments}}{\text{Gross monthly income}}\times100
]
Lenders use DTI to assess whether you can manage another monthly payment. The acceptable ratio varies by lender and loan program, and some may consider additional factors such as savings, credit history, and employment stability.
Estimate the proposed renovation loan payment before applying so you can determine whether it fits your budget.
Step 4: Compare Renovation Loan Options
Different financing options suit different circumstances. Compare interest rates, annual percentage rates (APRs), fees, repayment periods, collateral requirements, and funding timelines.
For instance, an unsecured personal loan may be appropriate when you need a fixed amount and do not want to pledge your home as collateral. A home equity loan may be worth considering if you have sufficient equity and prefer a potentially lower rate.
The right option depends on more than the advertised interest rate. Review the total amount you will repay over the life of the loan.
Step 5: Gather Your Documents
Lenders may request documents to verify your identity, income, debts, property ownership, and renovation plans.
Common documents include:
- Government-issued identification
- Recent pay stubs or other income records
- Tax returns or bank statements, where required
- Details of existing loans and monthly obligations
- Contractor estimates and renovation plans
- Property information and mortgage statements for equity-based financing
Requirements differ by lender and loan type. Preparing these documents in advance can help reduce delays.
Step 6: Apply and Compare Loan Offers
Submit applications to suitable lenders and review the terms carefully. Where available, prequalification may let you view estimated terms with a soft credit inquiry, although the process varies and does not guarantee approval.
Compare the APR, monthly payment, repayment term, origination fees, late fees, prepayment terms, and any collateral requirements.
Before accepting an offer, confirm whether the funds can be used for your intended renovation and whether the lender imposes contractor or project restrictions.
Step 7: Review the Agreement Before Signing
Read the complete loan agreement before accepting the money. Confirm the loan amount, interest rate, payment schedule, fees, and consequences of missed payments.
For secured loans, understand what could happen if you default. A loan secured by your home can put your property at risk.
Once the loan is finalized and the funds are available, use them according to your project budget and keep records of renovation expenses.
Best Types of Loans for House Renovations
There is no single best renovation loan for every homeowner. The following options differ in cost, eligibility, funding structure, and risk.
1. Personal Loans for Home Renovations
A personal loan is often an attractive choice for homeowners who want a fixed amount without using their property as collateral. Many personal loans are unsecured, meaning approval depends largely on factors such as creditworthiness, income, and existing debt.
Advantages:
- No home equity is generally required for unsecured loans.
- Fixed-rate loans provide predictable monthly payments.
- Funding may be available relatively quickly.
- Funds may be used for a wide range of eligible improvements.
Disadvantages:
- Interest rates may be higher than those on some secured loans.
- Loan limits may not cover major additions or extensive remodeling.
- Fees and credit requirements vary by lender.
Personal loans may suit smaller or medium-sized projects when the homeowner can comfortably afford the repayment schedule.
2. Home Equity Loans
A home equity loan allows eligible homeowners to borrow against the equity they have built in their property. It commonly provides a lump sum with a fixed interest rate and scheduled payments.
Equity is generally the difference between the home’s current value and the outstanding mortgage balance, although lenders use their own valuation and eligibility rules.
Advantages:
- A fixed rate can make payments easier to plan.
- Loan amounts may accommodate larger projects.
- Rates may be lower than those on unsecured personal loans.
Disadvantages:
- The home serves as collateral.
- Closing costs and appraisal fees may apply.
- Approval may take longer than an unsecured loan.
A home equity loan may be appropriate for a major renovation when you have sufficient equity and a reliable repayment plan.
3. Home Equity Lines of Credit (HELOCs)
A HELOC is a revolving credit line secured by home equity. Rather than receiving the full amount at once, borrowers can draw funds as needed, subject to the credit limit and agreement.
This arrangement can be useful when renovation work occurs in stages or when costs are uncertain.
However, many HELOCs have variable interest rates, so payments can increase. They may also have draw periods, repayment periods, annual fees, or other charges.
Because your home secures the debt, consider the risks carefully before borrowing.
4. FHA 203(k) Rehabilitation Loans
The Federal Housing Administration’s 203(k) program allows eligible borrowers to finance the purchase or refinancing of a home and qualifying rehabilitation costs through a single FHA-insured mortgage.
This program may be useful for buyers purchasing a property that needs repairs or homeowners undertaking eligible rehabilitation through a qualifying refinance.
The program has specific property, borrower, project, contractor, and documentation requirements. It is not a general-purpose personal loan, and funds are subject to program rules.
Ask an FHA-approved lender whether your property and proposed renovation qualify.
5. Fannie Mae HomeStyle Renovation Loans
A HomeStyle Renovation mortgage can combine eligible renovation expenses with a home purchase or refinance under the program’s requirements.
It may allow a wider range of improvements than some narrowly focused repair programs, subject to eligibility, appraisal, renovation, and lender rules.
This option may be worth investigating if you are buying a home that needs improvements or refinancing an existing property to fund a renovation.
6. Cash-Out Refinancing
Cash-out refinancing replaces an existing mortgage with a new, larger mortgage and provides eligible borrowers with some of the difference in cash after paying off the original loan and applicable costs.
It can provide funds for substantial improvements, but the overall cost depends on the new interest rate, closing costs, repayment term, and the amount borrowed.
If your current mortgage has a favorable interest rate, refinancing could be less attractive than a personal loan or home equity product. Compare the full cost rather than focusing only on the monthly payment.
7. Government, State, and Local Assistance Programs
Some government agencies, states, municipalities, and nonprofit organizations offer assistance for specific home repairs or improvements. Programs may focus on energy efficiency, accessibility, weatherization, health and safety hazards, or repairs for eligible households.
Availability and eligibility vary based on income, location, property type, and project purpose. Some programs offer grants or subsidized financing rather than conventional loans.
Check official federal, state, and local housing resources before assuming you must pay for every project through commercial borrowing.
How Much Can You Borrow for Home Renovations?
The amount you can borrow depends on your income, credit profile, existing debts, property equity, lender policies, and the type of loan.
Unsecured personal loans are limited by the lender’s underwriting criteria and may offer less funding than equity-based financing. Home equity loans and HELOCs depend partly on property value, outstanding mortgage debt, and the lender’s permitted loan-to-value limits.
For renovation mortgages, the eligible amount may also depend on the property’s value, the planned improvements, and program-specific rules.
Estimate the amount you need before applying. A larger loan can increase interest costs and financial pressure, even when the lender approves it.
What Credit Score Do You Need for a Renovation Loan?
There is no universal minimum credit score for every home renovation loan. Requirements depend on the lender, loan product, and whether the financing is secured or unsecured.
Borrowers with stronger credit may qualify for more favorable terms, while those with limited or damaged credit may face higher rates, lower borrowing limits, or stricter documentation requirements.
If your credit score is low, consider reviewing your credit reports, reducing outstanding balances where possible, and comparing lenders that evaluate more than credit scores alone.
Be cautious of guaranteed-approval promises, large upfront fees, and lenders that do not clearly disclose their terms.
Can You Get a Home Renovation Loan With Bad Credit?
It may be possible, but options can be more limited and expensive. Some lenders consider income, debt obligations, employment history, collateral, and other financial information alongside credit scores.
Potential approaches include:
- Comparing personal loans from reputable lenders that accept a wider range of credit profiles
- Considering a smaller project that requires less borrowing
- Exploring eligible local repair assistance programs
- Improving credit before applying, if the renovation is not urgent
- Comparing secured financing only after understanding the risk to your home
A secured loan is not automatically the best choice for someone with bad credit. Missing payments could put the property at risk, so borrow only when the repayment plan is realistic.
Is a Secured or Unsecured Renovation Loan Better?
A secured loan is backed by collateral, such as your home. An unsecured loan does not generally require collateral but relies more heavily on creditworthiness and repayment capacity.
| Feature | Secured loan | Unsecured loan |
|---|---|---|
| Collateral | Usually required | Generally not required |
| Home at risk if you default | Possible when the home secures the debt | Not directly pledged as collateral |
| Interest rate | May be lower | May be higher |
| Loan amount | May support larger projects | Depends on lender limits |
| Approval factors | Credit, income, equity, collateral | Credit, income, debts |
The best option depends on your financial circumstances, project size, and willingness to accept collateral risk.
How to Get Approved for a Home Renovation Loan
To strengthen your application, focus on the factors lenders can evaluate:
- Create a realistic budget. Know the amount required and avoid unnecessary borrowing.
- Check your credit reports. Correct errors before submitting applications.
- Reduce existing debt when practical. Lower monthly obligations can improve affordability.
- Document your income. Provide accurate and complete financial information.
- Compare multiple lenders. Review the APR, fees, eligibility rules, and repayment schedule.
- Prepare renovation estimates. Detailed plans and contractor quotes may help with project-based financing.
- Avoid misleading applications. Report your income, employment, debts, and intended loan use accurately.
Approval is never guaranteed, and submitting an application does not mean the lender has committed to fund the renovation.
Common Mistakes to Avoid When Borrowing for Renovations
Homeowners can reduce financial surprises by avoiding these common errors.
Borrowing without a detailed budget: A rough estimate may leave you short of funds or encourage unnecessary debt.
Choosing a loan based only on the interest rate: Fees, repayment terms, and variable rates can significantly affect total costs.
Ignoring collateral risks: Falling behind on a secured loan may have serious consequences, including foreclosure when the home secures the debt.
Underestimating project costs: Delays, hidden damage, permit requirements, and material changes can increase the final bill.
Using all available borrowing capacity: Being approved for a large amount does not mean you can comfortably repay it.
Failing to verify contractors: Check references, licensing requirements, insurance, written estimates, and payment schedules before committing to major work.
Ignoring local permits and building codes: Unapproved work can create safety problems, fines, and difficulties when selling or refinancing a property.
Alternatives to Taking Out a Renovation Loan
Borrowing is not the only way to finance home improvements. Depending on your circumstances, alternatives may include:
- Personal savings: Avoids interest and monthly debt payments.
- Phased renovations: Complete essential repairs first and postpone less urgent upgrades.
- Contractor payment schedules: Arrange payments tied to agreed project milestones, with appropriate contractual safeguards.
- Energy-efficiency incentives: Investigate eligible rebates, tax incentives, or local programs for qualifying improvements.
- Repair grants or assistance: Some programs support eligible households with essential repairs.
- A combination of savings and financing: Reduces the amount you need to borrow.
Compare the cost of borrowing with the benefit and urgency of the renovation. If a project is mainly cosmetic, delaying it until you have more savings may be financially sensible.
Is a Home Renovation Loan Worth It?
A renovation loan may make sense when the improvement is necessary, the project is well planned, and the monthly payments fit your budget. It can help you address safety issues, repair damage, improve accessibility, or make your home more suitable for your needs.
However, borrowing is less attractive when repayment would strain your finances, the renovation is not urgent, or the expected increase in property value is uncertain.
Do not assume every renovation will increase resale value by more than it costs. The result depends on your local housing market, the type of improvement, workmanship, and buyer preferences.
Evaluate the renovation’s practical benefits as well as its potential financial return.
Conclusion
Learning how to get a loan for house renovations begins with understanding your project costs, reviewing your finances, and comparing suitable financing options. Personal loans may work for smaller projects without home collateral, while home equity loans, HELOCs, and renovation mortgage programs may suit certain larger projects or eligible property purchases and refinances.
Before choosing a loan, compare APRs, fees, repayment terms, eligibility requirements, and collateral risks. Explore local assistance programs when appropriate, verify contractors, and borrow only what you can reasonably repay.
The right financing choice should help you improve your home without putting your long-term financial stability at unnecessary risk.
Frequently Asked Questions
1. How can I get a loan for house renovations?
Estimate your project costs, review your credit and income, compare personal loans and home equity financing, gather the required documents, and apply with a suitable lender. Choose a loan based on its total cost and your ability to repay it.
2. Can I get a renovation loan without home equity?
Yes. An unsecured personal loan may provide renovation funding without requiring you to use your home as collateral. Approval and loan terms depend on the lender’s credit, income, and debt requirements.
3. What is the easiest loan to get for home improvements?
The easiest option depends on your credit history, income, existing debt, and project size. An unsecured personal loan may involve a simpler process than a mortgage-based renovation loan, but approval is not guaranteed.
4. Can I get a home renovation loan with bad credit?
Possibly. Some lenders consider applicants with lower credit scores, although they may offer smaller loan amounts or higher interest rates. Compare reputable lenders and explore assistance programs before accepting expensive financing.
5. Are government loans available for home renovations?
Yes. Federal, state, and local programs may help eligible homeowners finance certain repairs and improvements. HUD offers programs such as FHA 203(k) rehabilitation mortgages and Title I property improvement loans. Eligibility and project restrictions apply.
6. Is a personal loan better than a home equity loan for renovations?
A personal loan does not generally require home collateral and may provide faster access to funds. A home equity loan may offer a lower interest rate for eligible borrowers, but your home secures the debt. Compare APRs, fees, repayment periods, and risks.
7. Can I use a renovation loan for a kitchen or bathroom remodel?
Many personal loans and home equity products can fund kitchen or bathroom remodeling. Renovation mortgage programs may have additional project and documentation requirements, so verify that your proposed work qualifies.
8. How long does it take to get a home renovation loan?
Funding times vary. Some personal loans can be funded within days, while home equity products and renovation mortgages may take several weeks or longer because of appraisals, underwriting, contractor documents, and closing requirements.
9. Does a home renovation loan increase property value?
It may, but an increase is not guaranteed. The result depends on the type of improvement, construction quality, local housing market, and buyer demand. Consider the practical benefits of the renovation as well as its potential resale value.
10. Can I get a renovation loan if I am still paying my mortgage?
Yes. Homeowners with an existing mortgage may qualify for a personal loan, home equity loan, HELOC, or eligible refinance-based renovation program. Approval depends on income, debt obligations, creditworthiness, equity, and lender requirements.
Read More: