Auto Loan Payment Calculator: Understand Costs Before You Buy
October 16, 2026
Buying a motorcycle can be an exciting step, whether you want a bike for daily commuting, weekend road trips, or long-distance touring. However, financing a motorcycle can become challenging if you have a low credit score, limited credit history, or no established credit. This is why many buyers search for motorcycle loan pre-approval with no credit check.
The idea of getting approved without a lender reviewing your credit history sounds appealing. It may seem like an easier way to find financing, understand your budget, and purchase the motorcycle you want. However, it is important to understand what lenders mean by “no credit check,” how motorcycle loan pre-approval works, and which financing options may be available to you.
In the United States, some lenders offer preliminary financing decisions based on limited information, while others consider applicants with poor or no credit history. Some may advertise no-credit-check financing but compensate for the additional risk with higher interest rates, larger down payments, or shorter repayment terms.
This guide explains how motorcycle loan pre-approval works, what alternatives are available when you want to avoid a hard credit inquiry, and how to compare financing offers before signing a loan agreement.
What Is Motorcycle Loan Pre-Approval With No Credit Check?
Motorcycle loan pre-approval is an initial assessment by a lender that indicates whether you may qualify for financing and, in some cases, provides an estimated loan amount, interest rate, or repayment term.
A traditional motorcycle loan application generally involves reviewing your credit history, income, existing debts, and other financial details. A no-credit-check offer claims that the lender will not review your credit report as part of its decision-making process.
However, the term can have different meanings depending on the lender.
For example, a lender might:
- Allow you to check potential loan offers without a hard credit inquiry.
- Evaluate your income and employment information before reviewing your credit.
- Consider applicants with poor or limited credit histories.
- Offer financing through a dealer that uses alternative approval criteria.
- Provide a preliminary decision without guaranteeing final loan approval.
Important: No-credit-check pre-approval is not necessarily the same as guaranteed financing. A lender may still verify your identity, income, employment, residence, and ability to repay the loan. Some lenders may also review credit information before final approval or funding.
Before submitting an application, ask the lender whether it performs a soft credit inquiry, a hard credit inquiry, or no credit inquiry at all.
Can You Get Pre-Approved for a Motorcycle Loan Without a Credit Check?
Yes, some financing providers advertise motorcycle loans without a credit check, but the availability and terms vary. You should not assume that every lender offering motorcycle financing will approve an applicant without reviewing credit.
Your options may depend on the motorcycle’s purchase price, your income, your down payment, your state of residence, and whether you are purchasing from a dealership or a private seller.
Here are some potential financing routes.
1. Lenders Offering Alternative Approval Criteria
Some lenders consider applicants whose credit history is limited or damaged. Depending on the lender, approval decisions may place greater emphasis on income stability, employment, bank account activity, down payment, or other evidence of repayment ability.
These lenders may still check credit. Therefore, alternative approval criteria should not automatically be interpreted as no-credit-check financing.
2. Motorcycle Dealership Financing
Some motorcycle dealerships work with multiple financing companies and may offer programs for buyers with less-than-perfect credit.
A dealership may help you compare available financing offers, but the dealer’s advertised approval process does not necessarily mean that your credit will not be checked. Ask which lender will review your application and whether the inquiry will be reported as a hard credit inquiry.
Also, compare the dealer’s complete financing offer with quotes from banks, credit unions, and other lenders.
3. Buy Here, Pay Here or In-House Financing
Certain dealers offer in-house financing, meaning they provide the loan directly rather than arranging financing through an outside lender.
Some may use income and down payment requirements when evaluating applicants. Others may check credit or use a combination of financial criteria.
Before accepting this type of loan, carefully review the interest rate, payment schedule, late fees, repossession provisions, and total repayment amount.
4. Personal Loans for Motorcycle Purchases
A personal loan may be an alternative if you want to purchase a motorcycle from a private seller or prefer not to use motorcycle-specific financing.
However, unsecured personal loans commonly involve credit and income assessments. A personal loan advertised as available to people with bad credit does not necessarily eliminate the credit check.
Check whether the loan allows motorcycle purchases, whether the rate is fixed or variable, and whether any origination fees apply.
How Does Motorcycle Loan Pre-Approval Work?
Understanding the pre-approval process can help you prepare the right information and avoid unnecessary applications.
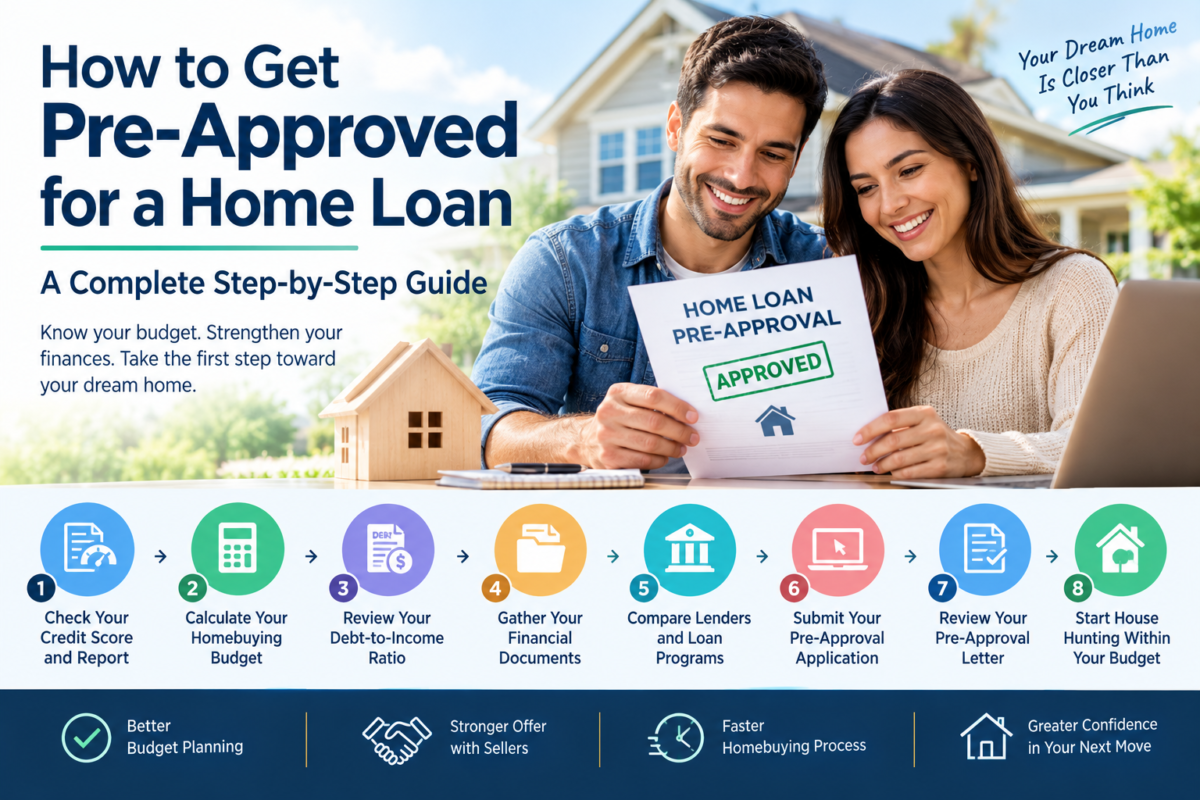
Step 1: Estimate Your Motorcycle Budget
Before contacting lenders, determine how much you can realistically afford.
Include more than the motorcycle’s advertised price. Your total budget should account for:
- Sales tax and registration fees.
- Dealer documentation or setup charges.
- Motorcycle insurance.
- Helmet, protective clothing, and safety equipment.
- Maintenance, tires, and repairs.
- Fuel and parking expenses.
For example, a motorcycle priced at $8,000 may cost more after taxes, registration, insurance, and dealer fees. Your financing needs should reflect the total purchase cost rather than the sticker price alone.
Step 2: Review Your Financial Situation
Even if you prefer a lender that does not check credit, you should understand your current financial position.
Review your monthly take-home income, housing costs, existing loan payments, credit card obligations, and regular expenses.
A lender may ask for proof of income, employment details, identification, residence information, or bank statements. Having these documents ready can make the application process easier.
Step 3: Compare Lenders and Pre-Qualification Options
Look for lenders that clearly explain their eligibility criteria and inquiry policies.
Pre-qualification may allow you to estimate your eligibility or review potential rates through a soft credit inquiry. A soft inquiry generally does not affect your credit score, although the lender may later perform a hard inquiry during the formal application.
Read the lender’s privacy policy and application disclosures before providing sensitive financial information.
Step 4: Submit the Required Information
Depending on the financing provider, you may need to provide:
- Full legal name and contact information.
- Proof of identity and residence.
- Employment and income details.
- Estimated loan amount.
- Information about the motorcycle.
- Down payment amount.
- Permission for any required credit inquiry.
Only submit personal and financial information through a lender’s verified website or another secure application channel.
Step 5: Review the Preliminary Decision
If the lender provides a pre-approval or pre-qualification result, review the estimated loan amount, annual percentage rate (APR), repayment period, fees, and down payment requirements.
A preliminary offer may change after income verification, vehicle valuation, credit review, or other underwriting checks.
Step 6: Complete Final Approval
Final approval may require additional documents, a formal loan application, verification of the motorcycle’s details, and signing the loan agreement.
Do not assume that a preliminary decision guarantees funding. Confirm the final loan terms before agreeing to purchase the motorcycle.
What Do Lenders Consider If They Do Not Check Credit?
A lender that does not use a traditional credit report may rely on other information to evaluate whether you can repay the loan. The exact criteria vary by provider.
Income and Employment Stability
A consistent income can help demonstrate your ability to make regular payments. A lender may request pay stubs, employment details, tax documents, or bank statements.
Self-employed applicants may need additional documentation, such as tax returns or business income records.
Down Payment
A larger down payment reduces the amount you need to borrow. It may also reduce the lender’s financial exposure if you cannot repay the loan.
For example, if a motorcycle costs $10,000 and you make a $2,000 down payment, you would need to finance $8,000 before applicable taxes and fees.
A larger down payment does not guarantee approval, but it can improve the affordability of the purchase.
Debt-to-Income Ratio
Your debt-to-income ratio (DTI) compares your monthly debt payments with your gross monthly income.
For example, if your gross monthly income is $4,000 and your monthly debt payments total $1,200, your DTI is 30%.
Some lenders use DTI to evaluate whether you can comfortably manage another monthly payment. Their acceptable thresholds vary.
Banking and Payment History
Some alternative lenders may review bank account activity, cash flow, or evidence of regular bill payments. This does not mean every lender uses these methods, and sharing banking information can create privacy risks.
Review what data the lender collects, how it uses that data, and whether you can revoke account access.
Motorcycle Value and Down Payment
For secured motorcycle loans, lenders may consider the bike’s value, age, condition, and resale potential. The motorcycle may serve as collateral, meaning the lender could repossess it following a default, subject to applicable law and the loan agreement.
Motorcycle Loans for Bad Credit or No Credit History
Having bad credit or no established credit history can make financing more difficult, but it does not automatically mean you cannot obtain a motorcycle loan.
The best approach depends on whether your credit history is damaged, limited, or nonexistent.
If You Have Bad Credit
If previous late payments, high credit card balances, or other negative credit events have lowered your score, consider these steps:
- Check your credit reports for inaccurate information.
- Reduce outstanding credit card balances when possible.
- Save for a larger down payment.
- Compare offers from multiple legitimate lenders.
- Avoid applying for several loans without understanding their inquiry policies.
- Consider a less expensive motorcycle to reduce the amount borrowed.
Some lenders specialize in borrowers with lower credit scores, but their interest rates and fees may be higher.
If You Have No Credit History
A limited credit history is different from a poor credit history. You may have little or no borrowing history for lenders to evaluate.
Potential alternatives include a lender that considers applicants with limited credit, a qualified co-signer, or saving for a larger down payment.
A co-signer may improve your application, depending on the lender’s policy, but that person becomes responsible for the debt if you fail to pay. Missed payments can also harm the co-signer’s credit.
If You Want to Avoid a Hard Credit Inquiry
Ask lenders whether they offer pre-qualification with a soft inquiry.
A soft inquiry generally does not affect your credit score. A hard inquiry, which may occur when you formally apply for credit, can affect your score.
Be aware that the lender may require a hard inquiry before making a final decision. Get confirmation of its process before submitting your application.
How Much Does a Motorcycle Loan Cost?
The cost of motorcycle financing depends on the loan amount, APR, repayment term, fees, and down payment.
APR is particularly important because it reflects the annual cost of borrowing and can include certain fees in addition to interest.
Consider the following simplified illustration for an $8,000 loan with a fixed APR and monthly payments. The figures are estimates and exclude taxes, insurance, and additional fees.
| Loan term | Illustrative APR | Approx. monthly payment | Approx. total payments |
|---|---|---|---|
| 36 months | 8% | $251 | $9,036 |
| 36 months | 18% | $289 | $10,404 |
| 60 months | 8% | $162 | $9,720 |
| 60 months | 18% | $203 | $12,180 |
These examples are for comparison only and do not represent current market rates or a guaranteed offer. Actual payment amounts depend on the lender’s terms.
A longer repayment term may reduce the monthly payment but increase the total interest paid. A higher APR can also substantially increase borrowing costs.
Before accepting financing, compare the total amount payable, not just the monthly payment.
Where Can You Find Motorcycle Financing With No Credit Check?
If you are searching for motorcycle loan pre-approval without a credit check in the United States, consider several types of providers.
Banks and Credit Unions
Banks and credit unions offer motorcycle loans or other financing products, depending on the institution. They commonly review credit, income, and debt obligations, but some may offer pre-qualification options or programs for applicants with limited credit.
Credit unions may have competitive terms for eligible members. Ask about membership requirements, minimum loan amounts, APRs, and fees.
Online Motorcycle Lenders
Online lenders can make it easier to compare financing options without visiting multiple locations. Some offer preliminary eligibility checks, while others require a full application.
Verify the lender’s identity, licensing where applicable, privacy practices, and complete loan terms before proceeding.
Dealership Financing Departments
A dealership may submit your application to several financing partners. This can be convenient, especially when you have already selected a motorcycle.
However, ask whether the dealership will send your application to multiple lenders, how inquiries will be handled, and whether the advertised rate is available to your credit profile.
Personal Loan Providers
Personal loan providers may offer financing that can be used for a motorcycle purchase. However, eligibility requirements vary, and many personal loans require a credit review.
Compare origination fees, APR, repayment periods, and any restrictions on how the loan proceeds may be used.
How to Avoid Motorcycle Loan Scams
Searching for no-credit-check financing can expose you to misleading advertisements and fraudulent offers. Be cautious when a provider promises approval regardless of income or financial circumstances.
Watch for these warning signs:
- Guaranteed approval claims: Legitimate lenders generally have eligibility requirements and may decline applications.
- Upfront payment demands: Be suspicious of demands for gift cards, cryptocurrency, or unusual payments before funding.
- Unclear loan terms: Avoid signing an agreement that does not clearly state the APR, fees, repayment schedule, and total amount due.
- Pressure to act immediately: Be wary of lenders that discourage you from comparing offers or reading the agreement.
- Unverified websites: Confirm the company’s identity and contact information independently.
- Requests for excessive personal information: Understand why sensitive data is needed and how it will be protected.
In the United States, you can check relevant state financial regulator resources and the Consumer Financial Protection Bureau (CFPB) for consumer guidance. You can also review complaints and business information, while remembering that no single listing or review proves that a lender is legitimate.
Never pay an alleged lender or broker simply because it promises to erase your credit problems or guarantee a motorcycle loan.
Tips for Improving Your Chances of Motorcycle Loan Approval
You may be able to strengthen your application without relying on a no-credit-check loan.
Save for a Larger Down Payment
A larger down payment lowers the amount you need to finance and can reduce your monthly payments.
Choose an Affordable Motorcycle
Consider a reliable used motorcycle or a less expensive model. Borrowing less can make the loan easier to manage.
Demonstrate Stable Income
Prepare recent income records and accurate information about your employment or self-employment. Lenders may be more comfortable when they can verify your ability to repay.
Consider a Co-Signer Carefully
A financially strong co-signer may help you qualify with certain lenders. However, both parties should understand the legal and financial responsibilities involved.
Compare Multiple Offers
Do not accept the first financing offer you receive. Compare APRs, fees, loan terms, prepayment conditions, and total repayment costs.
Avoid Unnecessary Add-Ons
Dealers may offer optional products such as extended warranties, maintenance packages, or other protection plans. Some products may be useful, but they can increase the amount financed. Review each one separately before agreeing.
Questions to Ask Before Accepting a Motorcycle Loan
Before signing a financing agreement, ask the lender:
- Do you perform a soft credit inquiry, a hard inquiry, or no credit inquiry?
- Is this a pre-qualification, pre-approval, or final approval?
- What is the APR, and is the rate fixed or variable?
- What down payment is required?
- What is the total amount I will repay over the life of the loan?
- Are there origination fees, late fees, or other charges?
- Can I pay off the loan early without a penalty?
- Is the motorcycle used as collateral?
- What happens if I miss a payment?
- Can I review the full loan agreement before accepting the offer?
Clear answers to these questions can help you identify the true cost of financing and avoid unexpected obligations.
Is Motorcycle Loan Pre-Approval Without a Credit Check Worth It?
Motorcycle loan pre-approval without a credit check may be worth exploring if you have limited credit history, are concerned about a hard inquiry, or want to understand your financing options before visiting a dealership.
However, it should not be your only option. A lender that does not check credit may charge a higher APR or impose stricter terms. In some situations, a soft-credit-check pre-qualification from a traditional lender may offer a better balance between convenience and affordability.
Focus on the complete financing agreement rather than the promise of easy approval. A loan that appears convenient today can become expensive if its interest rate, fees, or payment schedule do not fit your budget.
Final Thoughts
Finding motorcycle loan pre-approval with no credit check in the United States can be challenging, but buyers with poor or limited credit may still have financing options. Alternative lenders, dealership programs, credit unions, and personal loans are all worth researching, provided you understand their eligibility requirements and costs.
Start by establishing a realistic budget, comparing lenders, checking whether pre-qualification uses a soft inquiry, and reviewing the APR and total repayment amount. If a lender advertises guaranteed approval, refuses to disclose fees, or pressures you to pay upfront, proceed with caution.
The goal is not simply to get approved for a motorcycle loan. It is to find financing you can repay comfortably while protecting your financial stability.
Frequently Asked Questions
1. Can I get a motorcycle loan with no credit check?
Some lenders advertise motorcycle financing without a credit check, but availability varies. Many still evaluate income, employment, debt obligations, or other financial information. Confirm the lender’s exact requirements before applying.
2. Can I get motorcycle loan pre-approval with bad credit?
Yes, some lenders consider applicants with bad credit. Approval depends on factors such as income, down payment, debt obligations, motorcycle value, and lender-specific requirements. You may receive a higher APR than a borrower with strong credit.
3. Does motorcycle loan pre-qualification affect my credit score?
Pre-qualification using a soft credit inquiry generally does not affect your credit score. A formal application may involve a hard inquiry, which can affect your score. Ask the lender which type of inquiry it uses at each stage.
4. Can I finance a motorcycle with no credit history?
Potentially. Some lenders consider applicants with limited credit histories, while others may require a co-signer, a larger down payment, or additional proof of income. Requirements vary by lender.
5. Is no-credit-check motorcycle financing more expensive?
It can be. Some lenders offering financing without traditional credit checks charge higher interest rates or fees to compensate for perceived risk. Compare the APR, total repayment amount, and all fees before deciding.
6. Can I get a motorcycle loan without a down payment?
Some lenders may offer financing with no down payment, but eligibility and terms vary. A down payment can reduce your loan balance and monthly payment, potentially making the purchase more affordable.
7. Can I buy a used motorcycle with no credit check?
Some dealers or financing providers may advertise alternative financing for used motorcycles. They may consider the motorcycle’s age, value, condition, and your income. Confirm whether a credit check is required and review the loan terms carefully.
8. How long does motorcycle loan pre-approval take?
Some online providers return preliminary decisions quickly, while others need additional information or manual review. Final approval and funding can take longer because of verification, documentation, and vehicle requirements.
9. What documents do I need for a motorcycle loan?
Depending on the lender, you may need government-issued identification, proof of residence, income documentation, employment details, bank statements, and information about the motorcycle and down payment.
10. What is the safest way to find motorcycle financing with no credit check?
Research the lender independently, confirm whether it conducts a credit inquiry, compare written loan offers, and review the APR and total repayment amount. Avoid guaranteed-approval promises, unclear agreements, and suspicious upfront payment requests.
Read More: